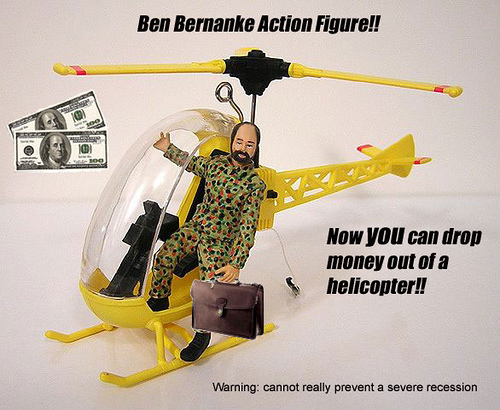
The market ran faster today than Roman Polanski going to get his keys to pick the baby sitter up because the manufacturing sector grew at its slowest pace since December, private construction spend dipped for the second month in a row, and Ben Bernanke said shit still sucks out there. So rally fucking on like Donkey Kong having his way with the princess, only if the princess had tainted his banana wth AIDS.
With the market rallying on macro news that was about as positive as a RuPaul pregnancy test, Money McBags is left to wonder what he is missing, how much the market would rally if there were actually something positive going on in the economy (like maybe either the second derivative of released data positively increasing or the unemployment rate decreasing and not from just from a declining labor force participation rate), and how he overlooked this delightful NSFW Alice Eve scene which has caused his Oscar to stand and applaud. Money McBags is not quite sure how to interpret the market moving in opposition to macro data, as the language of giberrish wasn't on the rosetta stone the last time he checked, but he hopes those of you buying in to this capitualting market are careful.
As for macro news, Benny B warned us that "we have a considerable way to go to achieve full recovery in our economy, and many Americans are still grappling with unemployment, foreclosure, and lost savings, in addition to the angst and nausea they feel every time they look at the deficit and realize their kids may be more fucked than Stephen Hawking in a duel." Ok, perhaps that last bit was made up but, whatever. Bennie B did get slightly positive by saying he fully expects consumer spend to pick up in the next few quarters as wages rise, business demand picks up, and the US finally figures out what to do with all of the underwear they stole.
Money McBags is a bit skeptical of Bennie B's claims since unemployment remains more stagnant than the Terri Moulton Horman for "Stepmother of the Year" campaign or jokes here on the great When Genius Prevailed so it's not clear where these rising wages are going to come from unless it's from laying more people off and then giving those still employed a bit of the saved salary, which of course would do nothing for overall consumer demand. But hey, when Bennie B gets his Fed on, the market listens (to the parts it wants to hear).
In other macro news, the ISM came out with their numbers for July and the manufacturing sector grew at its slowest pace this year, but luckily, the 55.5 number was better than the 54.2 analyst had guessed so rally on my friends. It was the third straight month (and the month was so straight it even got it up for a Kathy Najimy-Rachel Ray threesome) of slower growth but remember, readings above 50 still signal expansion, so apparently there is nothing to see here (except for new orders dropping to their lowest level in over a year, production slowing down, and Kagney Linn Karter).
In the final bit of macro news, construction spending rose .1% as increased investment in public projects (perhaps maybe a bridge to somewhere) offset the 15th straight monthly decline in private nonresidential construction and the .8% decline in private homebuilding (which included growth from the Greenspanville's being erected across the country, and yes, Money McBags said erected). Yowsa. As usual, last month's new construction was revised downward from a .2% drop to a 1% drop as part of the government's "hold the shock and hope for no awe" strategy, so this month's .1% decline should be labeled as "wishful thinking."
Internationally, China's manufacturing sector cooled further as the government tries to reign in reckless speculation on real estate and ben wa balls. The official purchasing managers' index fell to a 17 month low of 51.2 from 52.1, a separate PMI released today by HSBC and Markit Economics showed a drop to 49.4 from 50.4, and a third reading of PMI from the desk of Sum Dum Gai simply took the average of the two. China's ec0nomy slowing down is actually favorable as it has been growing at a rate less sustainable than a conversation involving only eye contact with Christina Hendricks so having it moderate a bit and perhaps not inflate to a bubble like every other emerged economy would be beneficial for all involved.
Driving the market today was the European banking sector thanks to HSBC putting down its fag, rolling up its sleves, and earning the fuck out of some profits. The bank doubled its profits to $7B despite revenue growth declining by 7%, operating expenses increasing by 9%, and no one having any fucking money. Profits rose as losses on bad loans tumbled to $7.5B, just over half of last year's losses, and were the result of bad loans rolling off the books and the bank not lending anyone any money. BNP Paribas also put up a good Q, with the French bank's profits rising due to credit getting better and having Laetita Casta on call to help coax out customer deposits. Just like in the US, bank profitablity seems to be rising across the globe despite declining revenues as credit is improving. That said, credit can only drive earnings for so long until the banks are going to have to start lending to people again to drive revenue and thus the vicious cycle will begin anew.
In other market news, Blackberry is not just losing market share to the iPhone but now the UAE said they will cut RIMM's data service like the dirty infidel that it is. The UAE cited security concerns over RIMM's reliance on encrypted emails which make it easier for criminals to operate and harder for the government to watch that stupid fucking video of the double rainbow that everyone seems to be emailing around. Not since Peter Chung anointed himself King has there been an international email controversy like this and it does not augur well for RIMM's jobs overseas going forward as other countries like Saudi Arabia are also thinking about taking steps to ban Blackberry's mobile services.
Finally, KO got an upgrade today from JP Morgan on the strength of the company's emerging markets and having read Money McBags' columns about the solid brand equity overseas the company enjoys. An article in Baron's also pimped KO today, saying it could rise by at least 10% in the next year because of North American markets and because it still tastes better than water. And last but not least, Corning was up nearly 6% on news that it's 50 year old Gorilla glass could be the next bazillion dollar product for flat screens and touch screens as it is 2 to 3 times stronger than regular glass, half the thickness, and sells for only a few bananas. The lighter, sturdier glass should cut down on shipping costs and scratched screens while also being easier to clean after one gets done with a chat roulette session.
In small cap news, everything was up. Money McBags is short on time today but he wants to highlight KIRK which remains too fucking cheap even though it was up strong today. Money McBags broke KIRK down a little over month ago saying its low end market focus (midwestern/southeastern housewives who love tchotchkes more than Joanie loves Chachi), growth through the downturn (and now they are going to be opening stores instead of closing them), and valuation (it is now trading ~9x to 10x eps estimates not including the $3.50 per share of cash on the balance sheet) make it almost as attractive as Diora Baird, and nothing has changed since then except for John Kyl's stand on the 14th Amendment. The other interesting small cap name is NTRI who traded down big on Friday after what Money McBags thought was an OKish quarter. He has to go through it in more detail and while he wouldn't be a buyer of the stock until their management team actually performs (they are 0 for the last bazillion quarters, rounding up to the nearest bazillion), they pay a nice yield, have a terrific cost structure, and are in a growing (pun intended) market. It's worth keeping on a watch list for when/if they can figure out how to start accelerating their growth rates (Money McBags votes for getting Nicole Eggert as a spokeswoman, but that's just him).
Showing posts with label RIMM. Show all posts
Showing posts with label RIMM. Show all posts
Monday, August 2, 2010




Wednesday, July 28, 2010
7/28/10 Midevening Report: Rally comes to an end and unfortunately it's not Jessica Biel's
The market sold off today as it couldn't keep ignoring the data and finally had to come to grips with where the bad macro news had touched it. The biggest negative was the Fed's Beige Book report which failed to titillate the market like either Money McBags' book report on the Kama Sutra (which he described as both thought provoking and delicious) or Fonzie's little black book.
In Bernanke's beige book we found out that economic activity has slowed in some areas and that Federal Reserve Bank President of Cleveland Sandra Painalto doesn't let you get to second base on the first date (Newsflash Sandy: If you ever want to get out of Cleveland, you're going to need to loosen up a bit, lower your reserve standards, and give Bennie B. some of that gold you've been hoarding). Eight of the twelve regions tracked by the Fed saw growth including New York, Richmond, and Andy Roddick's pants (he is married to her, you know that right?), while Atlanta and Chicago saw a slowdown, and Cleveland and Kansas City held steady. The Fed cited high unemployment, an ailing housing market, and consumers being more fucked than Lisa Ann in I'm a MILFaholic as reasons for the slower than hoped for recovery.
In other macro news, durable goods orders fell by 1% in June while analysts had guessed they would rise by 1% which makes guesses just an absolute value sign away from being correct which is a fuckload better than usual. Orders for long lasting goods like machinery, metals, and herpes were down the most they have been in almost a year and a half. Even worse, non-defense aircraft orders tumbled 25.6% after falling 30.2% last month as airlines brace for the continuing growth of staycations and poverty.
Finally, mortgage applications fell 4.4% last week but were led by a 5.9% drop in refinancings as rates ticked up 10bps and anyone who still owns a non-foreclosed upon home has pretty much already refinanced it. Surprisingly new home purchase mortgage applications were up 2% but since the majority of those will likely be rejected, that 2% number is more fictitious than the easter bunny, santa claus, or male affectionate lesbians.
In stock news, RIMM jobbed it's way up today despite the bad taste it has left in investors' mouths as of late. Rumors are that the company will be launching a new operating system and potentially a new keypad before officially giving up to AAPL and thus becoming the second biggest thing to ever be defeated at Waterloo (fyi, RIMM's headquarters are in Waterloo, Ontario).
Also, BA nosedived a bit after reporting a strong bottom line but a weak topline which was down 10% from last year. The company did reaffirm guidance which was slightly below analyst guesses but BA promised their new 787 would be more spacious and thus allow more opportunities for flyers to join the mile high club. And finally, Moody's lowered their ratings on banks BAC, C, and WFC from stable to negative citing lessened government support for banks under new regulations and something about shitty track records which means those banks are going to eventually need that lessened government support. And if any company knows what a poorly run company who sucks at their jobs looks like, it is certainly Moody's who never saw a huge market collapse it couldn't misinterpret.
In small cap news, beta sold off as these stocks had run strongly over the past week or so as if they were trying to catch a glimpse of the delightful Melissa Archer and thus it's not surprising that investors would want to take profits. CTGX reported last night and results were pretty much inline with Money McBags' expectations. The company grew revenue 21% thanks to both strong staffing and health care services businesses. Health care services is now 27% of revenues and should start driving this business like Nipsey Russell drove all of the housevies crazy on the Hollywood game show circuit in the 1970s. In addition to a solid topline, SG&A was down 120bps, operating margins were up from 3.6% to 4.3%, and EPS went from $.09 to $.12.
The stock sold off on the day though due to the general market taking it in the yingus and lowered full year EPS guidance by CTGX due to a reduction in demand for solutions work from one of their large customers in their energy practice. Excuse me while Money McBags yawns on this one. Full year revenue guidance was increased to $320MM to $328MM from $314MM to $322MM (which is 18% growth) while eps guidance was reduced to $0.45 to $0.51 from $0.47 to $0.55 and although it is down, it is still a 26% increase from 2009. But the point is, Money McBags gives less of a shit about 2010 guidance than he does about Alan Greenspan's thoughts on the housing, Nassim Taleb's thoughts on lyrical prose, or Audrina Patridge's thoughts on anything other than which hole to enter.
As said frequently in this space, the coming electronic medical records implementations (and they are coming because the government has mandated them, not just because they ran in to Sonya Kraus in the hallway) are going to be huge for CTGX. As the CEO said in the press release: "We believe we are still in the early stages of the significant increases in demand expected for EMR assessments, systems implementation, and development work."
This Q, EMR was 1/2 of their health care business which was ~$10MM in revenue and means they were working on 13-20 installations at ~$2MM-$3MM a project annually. But the thing is, only ~10% of hosptials have EMR and they are MANDATED by the fucking government to have them at least underway by 2014 so this business should scale faster than a business selling bronzer, or Valtrex, on the Jersey Shore.
Money McBags has gone through his valuation on CTGX here on When Genius Prevailed many times, so feel free to throw it in the search box, but this company is set for strong growth over the next few years so use this sell off as a potential buying opportunity. Obviously the lack of trading volume and the fact that CTGX's boring staffing business is still ~70% of their revenues is a concern, but as long as EMR is on the way and this company isn't full of shit about their ability to service that sector as aplombly as Bunny De La Cruz services the ding dong sector, the company should see solid growth.
And remember, When Genius Prevailed is on Facebook and Twitter.

In Bernanke's beige book we found out that economic activity has slowed in some areas and that Federal Reserve Bank President of Cleveland Sandra Painalto doesn't let you get to second base on the first date (Newsflash Sandy: If you ever want to get out of Cleveland, you're going to need to loosen up a bit, lower your reserve standards, and give Bennie B. some of that gold you've been hoarding). Eight of the twelve regions tracked by the Fed saw growth including New York, Richmond, and Andy Roddick's pants (he is married to her, you know that right?), while Atlanta and Chicago saw a slowdown, and Cleveland and Kansas City held steady. The Fed cited high unemployment, an ailing housing market, and consumers being more fucked than Lisa Ann in I'm a MILFaholic as reasons for the slower than hoped for recovery.

In other macro news, durable goods orders fell by 1% in June while analysts had guessed they would rise by 1% which makes guesses just an absolute value sign away from being correct which is a fuckload better than usual. Orders for long lasting goods like machinery, metals, and herpes were down the most they have been in almost a year and a half. Even worse, non-defense aircraft orders tumbled 25.6% after falling 30.2% last month as airlines brace for the continuing growth of staycations and poverty.
Finally, mortgage applications fell 4.4% last week but were led by a 5.9% drop in refinancings as rates ticked up 10bps and anyone who still owns a non-foreclosed upon home has pretty much already refinanced it. Surprisingly new home purchase mortgage applications were up 2% but since the majority of those will likely be rejected, that 2% number is more fictitious than the easter bunny, santa claus, or male affectionate lesbians.
In stock news, RIMM jobbed it's way up today despite the bad taste it has left in investors' mouths as of late. Rumors are that the company will be launching a new operating system and potentially a new keypad before officially giving up to AAPL and thus becoming the second biggest thing to ever be defeated at Waterloo (fyi, RIMM's headquarters are in Waterloo, Ontario).
Also, BA nosedived a bit after reporting a strong bottom line but a weak topline which was down 10% from last year. The company did reaffirm guidance which was slightly below analyst guesses but BA promised their new 787 would be more spacious and thus allow more opportunities for flyers to join the mile high club. And finally, Moody's lowered their ratings on banks BAC, C, and WFC from stable to negative citing lessened government support for banks under new regulations and something about shitty track records which means those banks are going to eventually need that lessened government support. And if any company knows what a poorly run company who sucks at their jobs looks like, it is certainly Moody's who never saw a huge market collapse it couldn't misinterpret.


In small cap news, beta sold off as these stocks had run strongly over the past week or so as if they were trying to catch a glimpse of the delightful Melissa Archer and thus it's not surprising that investors would want to take profits. CTGX reported last night and results were pretty much inline with Money McBags' expectations. The company grew revenue 21% thanks to both strong staffing and health care services businesses. Health care services is now 27% of revenues and should start driving this business like Nipsey Russell drove all of the housevies crazy on the Hollywood game show circuit in the 1970s. In addition to a solid topline, SG&A was down 120bps, operating margins were up from 3.6% to 4.3%, and EPS went from $.09 to $.12.

The stock sold off on the day though due to the general market taking it in the yingus and lowered full year EPS guidance by CTGX due to a reduction in demand for solutions work from one of their large customers in their energy practice. Excuse me while Money McBags yawns on this one. Full year revenue guidance was increased to $320MM to $328MM from $314MM to $322MM (which is 18% growth) while eps guidance was reduced to $0.45 to $0.51 from $0.47 to $0.55 and although it is down, it is still a 26% increase from 2009. But the point is, Money McBags gives less of a shit about 2010 guidance than he does about Alan Greenspan's thoughts on the housing, Nassim Taleb's thoughts on lyrical prose, or Audrina Patridge's thoughts on anything other than which hole to enter.

As said frequently in this space, the coming electronic medical records implementations (and they are coming because the government has mandated them, not just because they ran in to Sonya Kraus in the hallway) are going to be huge for CTGX. As the CEO said in the press release: "We believe we are still in the early stages of the significant increases in demand expected for EMR assessments, systems implementation, and development work."

This Q, EMR was 1/2 of their health care business which was ~$10MM in revenue and means they were working on 13-20 installations at ~$2MM-$3MM a project annually. But the thing is, only ~10% of hosptials have EMR and they are MANDATED by the fucking government to have them at least underway by 2014 so this business should scale faster than a business selling bronzer, or Valtrex, on the Jersey Shore.
Money McBags has gone through his valuation on CTGX here on When Genius Prevailed many times, so feel free to throw it in the search box, but this company is set for strong growth over the next few years so use this sell off as a potential buying opportunity. Obviously the lack of trading volume and the fact that CTGX's boring staffing business is still ~70% of their revenues is a concern, but as long as EMR is on the way and this company isn't full of shit about their ability to service that sector as aplombly as Bunny De La Cruz services the ding dong sector, the company should see solid growth.

And remember, When Genius Prevailed is on Facebook and Twitter.
Friday, July 9, 2010
7/9/2010 Midafternoon Report: Investors get excited and take off their shorts to allow long exposure to grow
It's a quiet day newswise and thus the market is deader than the Cleveland Cavaliers as it awaits the start of earnings season next week. Dominating the news today are non-financial matters like LeBron James betraying his home town team (and Cavs owner Dan Gilbert is said to have slept with his johnson in a freezer as he has promised revenge and literally believes in the old adage that it is a dish best served cold), the US and Russia are trading captured spies (and it's a good thing Money McBags never ran in to accused spy Anna Chapman because he would have spilled his state secrets right to her face, and her chest), and as always, Hannah Hilton remains retired.

Internationally, other than a sumo wrestling gambling scandal throwing Japan in to a tizzy (and Money McBags would hate to be the officer in charge of the cavity searches in that case), news remains light. Jean-Claude Trichet was out talking again about the EU's financial crisis and he said that it is too early to claim the crisis is over, that bank stress tests should help the recovery process (wink, wink), and that there needs to be stricter penalties for countries who ignore the EU's deficit limits such as having to move to Latvia, having to hand copy the entire novel Pride and Prejudice while listening to the melodic soul singing of Celine Dion, and having all pictures of Zita Gorog taken away. Most interestingly, Monsieur Trichet maintained that austerity measures and cutting government spending will not hinder economic growth thereby figuratively pissing on John Maynard Keynes' ashes and Paul Krugman's soul (though Krugman clearly sold his soul to Mephistopheles years ago as it is the only way to explain his ascent to NYTimes columnist).

In the market, China renewed Google's license to operate in the country instead of revoking it or simply giving it to Sum Dum Gai. Google could have been forced to shut down their chinese operations but instead they will continue to allow users to opt-in to receive either censored or NSFW uncensored search results. In other news, RIMM is rocketing up today as NTP has filed a lawsuit against AAPL, GOOG, and others claiming their wireless handsets infringe on NTP's patent of awesomeness. RIMM had settled previously with NTP for $612MM so they are free from this round of lawsuits and thus, for a day at least, can enjoy their declining market share and substandard product in peace.

In small cap news, two ridiculously cheap stocks that Money McBags has written about before have started rallying proving the old value investor theory that what goes down, must go up (unless it's ZAGG). One of those is NTZ which a month ago and 20% above its open today, Money McBags said:
"buying shares of NTZ is dumber than jumping in to a Hot Tub Time Machine set for the 1980s and then going Lucky Pierre between Magic Johnson and Rock Hudson. You might as well have bought shares of Amercian Home Mortgage right as the subprime mortgage market was melting down, invested in Daguerreotypes in the mid 19th century, or hired Bernie Madoff to manage your assets."
As Money McBags explained before, NTZ (or more commonly known to longterm holders as NTZero) sells high end furniture, mainly in Europe, and seeing as how Europe is instituting a little something called austerity measures and high end furniture is a more expensive and discretionary purchase than caviar infused lobster tails or a night with Heather Vandeven, that doesn't bode well for the company. That said, NTZ is trading at <3.5x EV/EBITDA and has 1/3 of their market cap in cash (even though they burned some last Q). The point remains that this company is either going to blow through their cash and go out of business (5% chance), is eventually going to come out of this and be worth a fuckload more than it is today (70% chance), or is a total fraud since Italy's version of the SEC is likely more hands off than Richard Simmons at a Rick's Cabaret (25% chance). Money McBags will wager a couple of Vietnamese dongs (as always, his currency of choice) that this is a real company and while he has absolutely no idea when it will turn around, has no faith in the global economy rebounding, and still thinks owning a high end furniture maker in a global recession/depression is as wise as covering yourself in chocolate and shouting "fire" while standing in the doorway of a crowded theatre filled with overweight arsonphobia sufferers, at some point this stock should trade for at least 7x EV/EBITDA which makes it a double from here (unless the EBITDA falls off a cliff, though if it does, there is more of a cusion right now than in Jessica Biel's pants) but that may not happen until 2025, so act accordingly.

The other name that is runnning now is TSYS and Money McBags first wrote about them in February and since then they have done nothing but go down like they were auditioning for a role in The Curious Taste of Benjamin's Button. Their last quarter was decent enough and their guidance has been fine but margins have been compressing, there has been concern about government spending drying up, and it is harder to get one's arms around their business than it is for a young lass to get her arms around Whitezilla's "business" (and you can google that at your own risk). They have a number of sort of related yet disparate businesses including a mobile location based software business, a text message enabling license selling business, and a government satellite communications software business. The company announced a new deal with the Army last night that could pay them as much as $9.8MM through 8/2011. TSYS's EV is ~$325MM and their guidance remains for $80MM-$85MM EBITDA, so it is currently trading at ~4x EV/EBIDTA and oh by the way, they just grew EBITDA by 45% last Q and revenue was up by 30% (though most of it was driven by acquisitions in the commercial segment). Again, this is a bit of a confusing company and portfolio managers just don't want to spend the time learning the different businesses and the complicated way in which results are reported (honestly, try reading one of their quarterly earnings releases, it makes Thomas Pynchon seem like Dr. fucking Seuss). That said, it is ridiculously cheap and with the new contract, perhaps there is more faith that government spending for their technology will continue. The stock has pretty much spent all of 2010 dropping but it may finally have bottomed out (because how much lower can it really go?) so this might make a nice short term trade.
With the market rallying, if you're itching to go long it's best to pick up these already beaten down names than ones that can still fall when the rally ends next week. So if Money McBags were you, the first thing he would do is empty your bank account and take one hella long trip to Vegas, but the second thing he would do is spend some time this weekend trying to get a better handle on TSYS because there is a very good chance of a solid return at these levels.
So enjoy your weekend and remember to follow WGP on Facebook and Twitter.

Thursday, April 1, 2010
4/1/10 Midafternoon Report: A disappointing RIMM job
Before we get to the markets, Money McBags found a picture of the hottest female in the history of history and wanted to share it with his readers as a sign of his gratitude. This is the hottest female ever*, so you're welcome. Anyway, stocks are up today as macro data was more encouraging than a Stephen Hawking pinky raise or Anne Sullivan Macy. The ISM reported that manufacturing expanded at its fastest pace in 5 years to a whopping 59.6 (and if it had been 59.9 the market may have shot more loads than a Japanese bukakke film). Prices paid (cough, inflation, cough) drove the index higher while the unemployment gauge slipped once again. More importantly, first time jobless claims fell to 439k, while even more importantly, Audrina Patridge is hot. The Street is hoping that the 6k drop in first time unemployment claims will bode well for the Labor Department's unemployment report to be released tommorow on paper made from the tears of the homeless. However, providing the proverbial turd in the punchbowl, or the penis in the MFF scene, was a report released today by some firm called Challenger, Gray, and Christmas who bah humbugged on the labor market by reporting that job cuts accelerated in March. The outplacment firm announced that the pace of job cuts had increased 61% sequentially from February but optimists will point out that the job cuts were down 55% from March of last year. So hoo-fucking-ray. The economy is either better or worse depending on your comparison. It's like the old saying, in the land of the blind, the one-eyed man is king (though in the land of the blind, the one-eyed man better not develop macular degeneration because there sure as fuck won't be any ophthalmologists).
International markets are all a buzz today as Asia and Europe saw strong manufacturing reports which signal the recovery is coming. China's manufacturing expanded for a 13th consecutive month, Europe's manufacturing industry expanded at its fastest pace in three years, and somethng in Japan called the Tankan index of sentiment jumped from minus 25 to minus 14. April fucking fools!!!!!!! Oh wait, that data is actually real. Wow. The international markets may have found their Viagra or Peter Gowland's private photo collection.
In stock news, RIMM missed their earnings estimates by $.01 eps and their revenue estimates by 6%. So despite earning $1.27, showing better margins, and growing 18%, the stock is down 5%+. Money McBags is actually surprised it isn't down more because when a growth stock in a competitive market needs to make their numbers and whiffs, nothing good can happen. Goldman Sachs cut their rating on RIMM to sell and basically called them a has been in the handset market. Their products are less differentiated than a Dahm triplet and a whole lot less delicious. Money McBags puked out his RIMM shares because fool me once, shame on me, fool me twice and you can go fuck yourself.
In small cap news everything is up except for Chinese power generation company APWR who handed out fortune cookies with their earnings release yesterday that all read "suckers." Their guidance was 30% below analyst guesses who apparently were just chasing windmills when covering the stock (and that is funny because APWR produces windmills, but you all knew that anyway, right?). Also, there was a comment in yesterday's blog comment section asking about MLNK and Money McBags will address it here. The reader wanted to know what was going on with MLNK and if it is still a hold. Money McBags broke down their fuck awful quarter a few weeks ago and nothing has changed since then of which he is aware. They earned $13MM of EBITDA and said this upcoming Q was going to be worse while they would see some sequential improvement after that. Of course they also said that last quarter would be flat and it was down worse than a than a clinically depressed person who just lost their dog and had a virus wipe out their computer's porn collection, so who the fuck knows if management can be trusted. Their excuse for missing the quarter is still a little squirrely as they blamed their clients for delaying decision making but Money McBags doesn't quite get that. HP's revenues were up ~10% and HP is like 25% of MLNK's business, so why the fuck didn't that help drive revenues more? And if MLNK is earlier in the cycle, why did they not see revenues jump by more in the previous Qs or why is their revenue being impacted by clients delaying their decision making now (since decisions should have already been made for this upcoming cycle). The simple fact is the company is underperforming, but even so, they still earned $13MM of EBITDA in the Q. They have a $163MM in cash and a $375MM market cap so an enterprise value of $210MM. If you think their business bounces back after likely sucking this Q coming up (Money Mcbags' words, their guidance), then a $52MM EBITDA run rate is possible and thus they are trading at 4x that. The stock is cheap on that basis, but on an EPS basis, they'll probably be lucky to earn $.45 this year so are trading at almost 20x that for no growth. The EV/EBITDA and cash give us some downside protection so Money McBags sees no reason to sell, but he also thinks this is dead fucking money for a while. Their business should ramp with electronics sales (though it didn't despite HP being up 10% as Money McBags said earlier, so if someone can explain that, Money McBags is all ears), so if the economy can really come back, they should be able to grow the business. Look, it ain't fucking AAPL, but it is sort of cheap with a cash cushion that has some nice operating leverage. So in short, the downside seems a bit limited but the upside may be further away than Paris Hilton's Academy Award (One Night in Paris excluded).
*April fucking fools'.

International markets are all a buzz today as Asia and Europe saw strong manufacturing reports which signal the recovery is coming. China's manufacturing expanded for a 13th consecutive month, Europe's manufacturing industry expanded at its fastest pace in three years, and somethng in Japan called the Tankan index of sentiment jumped from minus 25 to minus 14. April fucking fools!!!!!!! Oh wait, that data is actually real. Wow. The international markets may have found their Viagra or Peter Gowland's private photo collection.
In stock news, RIMM missed their earnings estimates by $.01 eps and their revenue estimates by 6%. So despite earning $1.27, showing better margins, and growing 18%, the stock is down 5%+. Money McBags is actually surprised it isn't down more because when a growth stock in a competitive market needs to make their numbers and whiffs, nothing good can happen. Goldman Sachs cut their rating on RIMM to sell and basically called them a has been in the handset market. Their products are less differentiated than a Dahm triplet and a whole lot less delicious. Money McBags puked out his RIMM shares because fool me once, shame on me, fool me twice and you can go fuck yourself.

In small cap news everything is up except for Chinese power generation company APWR who handed out fortune cookies with their earnings release yesterday that all read "suckers." Their guidance was 30% below analyst guesses who apparently were just chasing windmills when covering the stock (and that is funny because APWR produces windmills, but you all knew that anyway, right?). Also, there was a comment in yesterday's blog comment section asking about MLNK and Money McBags will address it here. The reader wanted to know what was going on with MLNK and if it is still a hold. Money McBags broke down their fuck awful quarter a few weeks ago and nothing has changed since then of which he is aware. They earned $13MM of EBITDA and said this upcoming Q was going to be worse while they would see some sequential improvement after that. Of course they also said that last quarter would be flat and it was down worse than a than a clinically depressed person who just lost their dog and had a virus wipe out their computer's porn collection, so who the fuck knows if management can be trusted. Their excuse for missing the quarter is still a little squirrely as they blamed their clients for delaying decision making but Money McBags doesn't quite get that. HP's revenues were up ~10% and HP is like 25% of MLNK's business, so why the fuck didn't that help drive revenues more? And if MLNK is earlier in the cycle, why did they not see revenues jump by more in the previous Qs or why is their revenue being impacted by clients delaying their decision making now (since decisions should have already been made for this upcoming cycle). The simple fact is the company is underperforming, but even so, they still earned $13MM of EBITDA in the Q. They have a $163MM in cash and a $375MM market cap so an enterprise value of $210MM. If you think their business bounces back after likely sucking this Q coming up (Money Mcbags' words, their guidance), then a $52MM EBITDA run rate is possible and thus they are trading at 4x that. The stock is cheap on that basis, but on an EPS basis, they'll probably be lucky to earn $.45 this year so are trading at almost 20x that for no growth. The EV/EBITDA and cash give us some downside protection so Money McBags sees no reason to sell, but he also thinks this is dead fucking money for a while. Their business should ramp with electronics sales (though it didn't despite HP being up 10% as Money McBags said earlier, so if someone can explain that, Money McBags is all ears), so if the economy can really come back, they should be able to grow the business. Look, it ain't fucking AAPL, but it is sort of cheap with a cash cushion that has some nice operating leverage. So in short, the downside seems a bit limited but the upside may be further away than Paris Hilton's Academy Award (One Night in Paris excluded).

*April fucking fools'.
Tuesday, March 30, 2010
3/30/10 Midafternoon Report: Market rests today after spending all night trying to find the afikomen
Before we get to the market news, today marks an important achievement for mankind (perhaps an even more important achievement than Brooklyn Decker) as the Hadron particle collider is finally working sending two protons smashing in to each other at 99% the speed of light. Results hope to answer some of the Universe's most essential questions such as the existence of the Higgs Boson, the presence of dark matter, and who the fuck the people are who actually watch American Idol. So planet changing discoveries aside, the market is flat today as international concerns temper the moderately better than expected US macro data. Consumer confidence jumped thanks to the new health care bill, which has made it easy for people to buy deliriants. The index reached 52 today, easily besting the 46 from February, which would be all the more impressive if we actually knew what a difference of 6 points meant. Additionally, Home prices rose in the 20 city Case-Shiller index (named of course for "Hot" Karl Case and Bob Shiller) from "take this fucking thing off my hands" to "take this fucking thing off my hands but I am keeping the toaster." The index was up .3% sequentially and down .7% from a year ago which is the smallest y/y decline in two years. However, on an adjusted basis the index was down .4% sequentially due to the initial petering out (and yes, I said peter) of the government first time home buyer's tax credit and the realization that monopoly money is not a valid subsitute for cash or a claimable asset to mortgage guarantors. That said, there was some really interesting news that tax receipts are now expected to rise in the 15 most populous states by 2011 which would be huge for the economy (no joke, it would literally be bigger than Manuel Uribe at an all you can eat taco bar. Ok, maybe a little joke.). California has already taken in 3.9% more in taxes than forecast since December while NY is $129MM above budget. This is largely the result of higher sales tax receipts from increased consumer spend likely as a result of this rise in consumer confidence and the hiring of Jeffrey Skilling to audit all state tax records.
Internationally, S&P cut Iceland's local currency credit rating from BBB/A-2 to BBB/A-3 (and if Money McBags were rating Iceland, they would always be rated "frosty.). And yes, those are the actual fucking ratings S&P uses which are about as helpful as chopsticks to a leper. I mean really, BBB/A-2? Even Heidi Montag's singing career and Poncaire's Conjecture are less confusing (especially if you are tone deaf or Grigori Perelman). Money McBags hasn't seen anything so contrived since Ricky Martin acted straight in one of his videos. That said, the downgrade made Magnus ver Magnussen, a man so important they named him twice, pick up a giant boulder and crush the S&P's entire Iceland office. Anyway, Money McBags scoffs at any rating, no matter how confusing, by any rating agency due to the inherrent conflicts of interest and the piss poor track record of those ratings agencies (see US financial markets circa 2007). Of course this downgrade has caused investors throughout the world to not just try to locate Iceland on a map, but to learn for the first time that Iceland actually had credit ratings. In other international news, an auction of 1B euros of 12 year Greek bonds garnered interest in only 390MM euros worth of them which caused the offering to be more undersubscribed than Bernie Madoff's new investing magazine (tentatively titled, MisFortune). The lack of interest in the bonds (well, technically the interest is actually quite high at 5.9%) has caused the yield spread between Greek debt and German debt to double. Investors continue to worry about Greece's ability to fund themselves while Money mcBags bets in 1 year no one will remember any of this.
In stock news Apple is up on reports that they are designing an iPhone to be CDMA compatible thus potentially giving iPhone users a choice of carriers and not restricting them to AT&T. AAPL allowing competition is a bit like North Korea alowing photographers or Ellen Degeneres allowing penetration, but it should be positive for consumers and thus positive for the stock. In related news, RIMM announces earnings after the bell tomorrow and is limping in to that announcement. While Money McBags likes owning the number two competitor in a market about as much as he likes country music, RIMM is cheap for its growth trading at less than 20x earnings estimates. Money McBags is an owner of RIMM and will be holding it through the quarter because this should really be at least a $95 stock. That said, if they miss, look out below because RIMM will go down faster than Hillary Duff after getting an engagement ring.
In small cap news, CRUS seems to be riding the news of the potential newly designed iPhone and is up 6%+. Money McBags is an owner of CRUS (he mentioned he was buying in his 1/29 Midday Report where he said he "did dip his toe into the CRUS waters yesterday (and it was delightfully stripper piss warm))." The original analysis of CRUS was done on 1/12/09 but the company basically produces ICs for two sectors, audio and energy. In the audio market they won a chip in the iPhone a few quarters ago as their IC delivers better sound quality and as a result, that segment grew 83% last quarter and was 72% of sales. In the energy market, their business was hit harder than a bottle of Mad Dog by Betty Ford in the 1970s as sales dropped ~40% in the downturn. Their main energy segment involves selling chips that go into power meters and their biggest customer is Itron and Itron sales were up 10% last Q, so that could be a good indicator of this business coming back. Of course a better indicator is that they have had two sequential up quarters in the energy segment after bottoming out and that segment is what delivered their positive earnings surprise last Q. Money McBags thinks the company can earn ~$.65 in the fiscal year ending 3/2011 and that assumes just 10% growth in the audio segment (and remember they just grew 80% and could be getting more business if the Apple news from today is true) and 20% growth in the energy business. The 20% energy business growth is a bit aggressive because it has been down so much, but that growth assumes $18MM in revenue per quarter and before the downturn they were regularly doing $20MM-$24MM. The company has $2 in cash on it's balance sheet and is trading at ~13x Money McBags estimate (which may now be too low) including that cash. They could also earn ~$50MM in EBITDA in this next fiscal year and thus are trading at only ~8x EV/EBITDA. This stock is cheap and has a nice cash cushion (while Jessica Biel has a nice ass cushion). Money McBags doesn't like to own cyclical companies, but CRUS is in the spanktasitc part of the cycle so it is worth owning at these levels. In other small cap news, RICK continues to tumble (and remember, Money McBags sold last week, so phew) while KITD had their quarterly call and didn't disappoint. Money McBags previewed KITD's Q yesterday but will break it down for you tomorrow. Let's just say he found it titillating and is looking to add to his holdings.


Internationally, S&P cut Iceland's local currency credit rating from BBB/A-2 to BBB/A-3 (and if Money McBags were rating Iceland, they would always be rated "frosty.). And yes, those are the actual fucking ratings S&P uses which are about as helpful as chopsticks to a leper. I mean really, BBB/A-2? Even Heidi Montag's singing career and Poncaire's Conjecture are less confusing (especially if you are tone deaf or Grigori Perelman). Money McBags hasn't seen anything so contrived since Ricky Martin acted straight in one of his videos. That said, the downgrade made Magnus ver Magnussen, a man so important they named him twice, pick up a giant boulder and crush the S&P's entire Iceland office. Anyway, Money McBags scoffs at any rating, no matter how confusing, by any rating agency due to the inherrent conflicts of interest and the piss poor track record of those ratings agencies (see US financial markets circa 2007). Of course this downgrade has caused investors throughout the world to not just try to locate Iceland on a map, but to learn for the first time that Iceland actually had credit ratings. In other international news, an auction of 1B euros of 12 year Greek bonds garnered interest in only 390MM euros worth of them which caused the offering to be more undersubscribed than Bernie Madoff's new investing magazine (tentatively titled, MisFortune). The lack of interest in the bonds (well, technically the interest is actually quite high at 5.9%) has caused the yield spread between Greek debt and German debt to double. Investors continue to worry about Greece's ability to fund themselves while Money mcBags bets in 1 year no one will remember any of this.


In stock news Apple is up on reports that they are designing an iPhone to be CDMA compatible thus potentially giving iPhone users a choice of carriers and not restricting them to AT&T. AAPL allowing competition is a bit like North Korea alowing photographers or Ellen Degeneres allowing penetration, but it should be positive for consumers and thus positive for the stock. In related news, RIMM announces earnings after the bell tomorrow and is limping in to that announcement. While Money McBags likes owning the number two competitor in a market about as much as he likes country music, RIMM is cheap for its growth trading at less than 20x earnings estimates. Money McBags is an owner of RIMM and will be holding it through the quarter because this should really be at least a $95 stock. That said, if they miss, look out below because RIMM will go down faster than Hillary Duff after getting an engagement ring.
In small cap news, CRUS seems to be riding the news of the potential newly designed iPhone and is up 6%+. Money McBags is an owner of CRUS (he mentioned he was buying in his 1/29 Midday Report where he said he "did dip his toe into the CRUS waters yesterday (and it was delightfully stripper piss warm))." The original analysis of CRUS was done on 1/12/09 but the company basically produces ICs for two sectors, audio and energy. In the audio market they won a chip in the iPhone a few quarters ago as their IC delivers better sound quality and as a result, that segment grew 83% last quarter and was 72% of sales. In the energy market, their business was hit harder than a bottle of Mad Dog by Betty Ford in the 1970s as sales dropped ~40% in the downturn. Their main energy segment involves selling chips that go into power meters and their biggest customer is Itron and Itron sales were up 10% last Q, so that could be a good indicator of this business coming back. Of course a better indicator is that they have had two sequential up quarters in the energy segment after bottoming out and that segment is what delivered their positive earnings surprise last Q. Money McBags thinks the company can earn ~$.65 in the fiscal year ending 3/2011 and that assumes just 10% growth in the audio segment (and remember they just grew 80% and could be getting more business if the Apple news from today is true) and 20% growth in the energy business. The 20% energy business growth is a bit aggressive because it has been down so much, but that growth assumes $18MM in revenue per quarter and before the downturn they were regularly doing $20MM-$24MM. The company has $2 in cash on it's balance sheet and is trading at ~13x Money McBags estimate (which may now be too low) including that cash. They could also earn ~$50MM in EBITDA in this next fiscal year and thus are trading at only ~8x EV/EBITDA. This stock is cheap and has a nice cash cushion (while Jessica Biel has a nice ass cushion). Money McBags doesn't like to own cyclical companies, but CRUS is in the spanktasitc part of the cycle so it is worth owning at these levels. In other small cap news, RICK continues to tumble (and remember, Money McBags sold last week, so phew) while KITD had their quarterly call and didn't disappoint. Money McBags previewed KITD's Q yesterday but will break it down for you tomorrow. Let's just say he found it titillating and is looking to add to his holdings.


Monday, March 8, 2010
3/8/10 Midafternoon Report: Market more mixed than reviews of Oscar telecast (and for the record, Money McBags gave it two thumbs in the ears)
The market is quiet today, likely still in bed after staying up all night to watch something called The Hurt Locker win so many Oscars that that the people who couldn't get tickets to Avatar may now go see it (that is if Alice in Wonderland is also sold out and they hate fun). The biggest news in the markets today is that AIG sold the second of its crown jewels, their foreign life insurance business Alico, to Met Life for $15B and with both of the AIG family jewels gone, they now qualify for a spot in the 2010 Eunuch Olympics. A business hasn't sold off two profitable units like this since Pam Anderson downsized her boobs (of course she had them re-inserted faster than Warren Buffett talks up his own book because you always have to keep the things that make you money). This sale gives AIG enough cash to pay some of their debt back to Uncle Sam and thus keeps their proverbial kneecaps intact for at least another couple of months because Uncle Sam doesn't play when you have his money, just ask Wesley Snipes. Unfortunately, AIG still owes the US government another $50B and seeing as how they have now sold off two of their biggest profit centers and their business won't generate $50B in profits until sometime around the year "two thousand and go fuck yourself," it is unclear what tricks they will do next to appease Uncle Sam (Perhaps Uncle Sam will "lend out" some of AIG's CDS expertise to China to try to smooth over relations and yield a happy ending for the two super powers). You just don't take daddy's money and get away with it.
In stock news MCD same store sales were up 4.8% in February driven by overseas sales and the $1 menu in the US. Money McBags is an owner of MCD as he believes in their affordability and brand equity in the fast growing developing nations. So even if Money McBags won't get high off his own supply by refusing to eat the swill that they serve at McDonald's (he would rather eat a Gabourey Sidibe burger out of the bun than whatever it is they serve at MCD's), Money McBags believes in the company. In other large cap names, RIMM got an upgrade from the Bank of Montreal today which has driven the stock up almost 5%. The BMO analyst raised his price target to $88 citing expected strong Q4 sales, a potential guidance raise, and Apple aboot (BMO and RIMM are Canadian after all, eh?) to go out of business because iPhones are for sissies (ok, that last one may have been made up). Now look, Money McBags is never a fan of owning the second best competitor in a space (he'll go Bang Bus any day over Backseat Bangers), but he will admit that he owns some RIMM simply because it is as cheap as a homless man's balls for it's growth as it is trading at less than 20x 2010 EPS estimates and less than 15x 2011 eps estimates despite continuing to dominate the business handset market like Nipsey Russell dominated the 1970s game show circuit (where he did more than just fill in Brett Somers' blanks). RIMM is getting 20% topline growth and 30%+ bottomline growth and you're only paying 15x for that. The stock is still a reasonable buy but it is unlikely to be a longterm holding for Money McBags as their end game is becoming more challenging than playing herpes roulette with Paris Hilton.
In small cap news, apparently a fuckload of people dropped some acid this weekend and went down to the local IMAX to see Alice in Wonderland (and Money McBags would march his hairs to the IMAX if it were Alice Eve's wonderland they were showing. He'd definitely let young Ms. Eve mock his turtle while he chesired her cat.). IMAX theatres pulled in nearly $12MM this weekend as this 3D spectacle eclipsed even Avatar's opening run and led IMAX to sell out every seat they had for the entire weekend. This has sent IMAX stock up 9% but Money McBags is still not buying as the stock is expensive and the movement today is likely retail money on the announced headlines. IMAX could run some more as its momentum coming out of Oscar weekend could be so great that it attempts to defy the laws of physics and create a coefficient of restitution greater than 1, but this story is longer in the tooth than Kirsten Dunst. In other small cap news, EBIX annonuced their quarter and is trading down despite a 55% increase in revenue, a 53% increase in net income (operating leverage be damned), a 99.5% customer retention rate for the year, $12MM in cash flow for the Q, and a forward p/e less than 15x. Money McBags has written about EBIX many times as nothing about the company makes sense and their financials and business are more opaquely complex than the Weiner process of Brownian motion (and I can assure you that is nowhere as dirty as it sounds). The stock is ridiculously cheap based on the fundamentals of the business but shorts have been all over it due to aggressive acquisition accounting, receivables growth outpacing revenue, the CEO having a bigger ego than Joe Francis has, and a proclivity to switch auditors at the drop of a questionable debit. Short activity was addressed on the call as a caller brought up that short exposure has climbed from 200k shares to 10MM in six months and the fact that EBIX has changed their auditors more times than Heidi Montag changed her face. CEO Robin Raina addressed this with some kind of Jedi mind trick ping pong analogy (no really he did) and a quote from some Latin American intellect whose name yields zero google hits (the transcript from the call has Robin "Making it" Raina quoting some guy named Joe Moppi which is either spelled wrong or more fictitious than EBIX's growth rate, can we get an auditor on this?). Kidding aside, Money McBags still has no idea what to do with this company. He has a hard time believing it is total fraud but there is enough smoke to just keep him away from it. That said, if you can get comfortable with their numbers, the stock is ridonkuously cheap. Money McBags wouldn't short it, but as always, there are easier ways to make money (like KITD, MLNK, or CRUS).

In stock news MCD same store sales were up 4.8% in February driven by overseas sales and the $1 menu in the US. Money McBags is an owner of MCD as he believes in their affordability and brand equity in the fast growing developing nations. So even if Money McBags won't get high off his own supply by refusing to eat the swill that they serve at McDonald's (he would rather eat a Gabourey Sidibe burger out of the bun than whatever it is they serve at MCD's), Money McBags believes in the company. In other large cap names, RIMM got an upgrade from the Bank of Montreal today which has driven the stock up almost 5%. The BMO analyst raised his price target to $88 citing expected strong Q4 sales, a potential guidance raise, and Apple aboot (BMO and RIMM are Canadian after all, eh?) to go out of business because iPhones are for sissies (ok, that last one may have been made up). Now look, Money McBags is never a fan of owning the second best competitor in a space (he'll go Bang Bus any day over Backseat Bangers), but he will admit that he owns some RIMM simply because it is as cheap as a homless man's balls for it's growth as it is trading at less than 20x 2010 EPS estimates and less than 15x 2011 eps estimates despite continuing to dominate the business handset market like Nipsey Russell dominated the 1970s game show circuit (where he did more than just fill in Brett Somers' blanks). RIMM is getting 20% topline growth and 30%+ bottomline growth and you're only paying 15x for that. The stock is still a reasonable buy but it is unlikely to be a longterm holding for Money McBags as their end game is becoming more challenging than playing herpes roulette with Paris Hilton.


In small cap news, apparently a fuckload of people dropped some acid this weekend and went down to the local IMAX to see Alice in Wonderland (and Money McBags would march his hairs to the IMAX if it were Alice Eve's wonderland they were showing. He'd definitely let young Ms. Eve mock his turtle while he chesired her cat.). IMAX theatres pulled in nearly $12MM this weekend as this 3D spectacle eclipsed even Avatar's opening run and led IMAX to sell out every seat they had for the entire weekend. This has sent IMAX stock up 9% but Money McBags is still not buying as the stock is expensive and the movement today is likely retail money on the announced headlines. IMAX could run some more as its momentum coming out of Oscar weekend could be so great that it attempts to defy the laws of physics and create a coefficient of restitution greater than 1, but this story is longer in the tooth than Kirsten Dunst. In other small cap news, EBIX annonuced their quarter and is trading down despite a 55% increase in revenue, a 53% increase in net income (operating leverage be damned), a 99.5% customer retention rate for the year, $12MM in cash flow for the Q, and a forward p/e less than 15x. Money McBags has written about EBIX many times as nothing about the company makes sense and their financials and business are more opaquely complex than the Weiner process of Brownian motion (and I can assure you that is nowhere as dirty as it sounds). The stock is ridiculously cheap based on the fundamentals of the business but shorts have been all over it due to aggressive acquisition accounting, receivables growth outpacing revenue, the CEO having a bigger ego than Joe Francis has, and a proclivity to switch auditors at the drop of a questionable debit. Short activity was addressed on the call as a caller brought up that short exposure has climbed from 200k shares to 10MM in six months and the fact that EBIX has changed their auditors more times than Heidi Montag changed her face. CEO Robin Raina addressed this with some kind of Jedi mind trick ping pong analogy (no really he did) and a quote from some Latin American intellect whose name yields zero google hits (the transcript from the call has Robin "Making it" Raina quoting some guy named Joe Moppi which is either spelled wrong or more fictitious than EBIX's growth rate, can we get an auditor on this?). Kidding aside, Money McBags still has no idea what to do with this company. He has a hard time believing it is total fraud but there is enough smoke to just keep him away from it. That said, if you can get comfortable with their numbers, the stock is ridonkuously cheap. Money McBags wouldn't short it, but as always, there are easier ways to make money (like KITD, MLNK, or CRUS).


Friday, December 18, 2009
12/18/09 Midday Report: Earnings surprises abound as RIMM jobs naysayers and naysayers begrudgingly admit they kind of liked it
The big news moving the market up today is that several tech companies beat earnings. Leading the way was RIMM who destroyed analyst forecasts of $1.04 by dropping $1.23 to their damp bottom line and growing topline by 49%. They also raised guidance, margin forecasts, and the ire of PALM who once again fell short of expectations like all of Jaimee Grubbs' parent's hopes and dreams. Apparently people still like buying Blackberries even if they don't always work as the Curve is now the number one selling smart phone, so suck on that Apple and your beautiful, fully functional iPhone which is so awesometastic it will actually wipe and bidet you for no extra charge.
In other tech news, ORCL easily beat forecasts as more companies are buying the fuck out of whatever ORCL software does and that can only be positive, unless Oracle software is responsible for promoting Paris Hilton's album, the intelligent design theory, or trickle-down economics.
In macro news, German business confidence rose as the Business Climate Index predicted the climate is getting so much better that all rain showers will now be golden. The index managed to rise to a whopping 94.7, beating out expectations of 94.5 and we all know how great a .2 beat is of a number with no context, right? Actually, the number comes from a survey of 7,000 German firms across their biggest industries including manufacturing, construction, wholesaling, retailing, and scat film shooting. The longterm average is 96 so I guess everything in Europe is almost back to normal, just don't tell the Greeks.
And finally Money McBags favorite RICK met expectations and didn't give guidance but said the current $.19 quarterly eps is a decent range though the first two quarters this year should be stronger than that with the NBA all-star game in Dallas and the Super Bowl and Pro Bowl in Miami (no seriously, they said that). Unfortunately, no one on the call asked how revenues during the Super Bowl will be effected by Chris Henry's absence and Pac Man Jones' unemployment.
If you read the transcript from their call, which I highly recommend even though it's no Tolstoy (but it is an asshair better than any of that Dan Brown crap), you can even learn of RICK's successful recent Toys for Tots event in their NYC club and no, Money McBags is not making that up but yes he is pissed his parents never got him those kind of toys when he was a tot. The point is, this company is easily going to earn $.76 next year and is likely going to earn over $1.00 (where analyst estimates currently are). They are trading at ~10x a worse case scenario and 6x-7x a more reasonable estimate. The problem is that RICK's is always one hummer in the champagne room away from being screwed (pun intended) so Money McBags recommends you go long RICK and buy some long dated out of the money puts to cover your ass should that happen (though he also recommends that RICK employees do everything but cover their asses).
Enjoy the weekend.
In other tech news, ORCL easily beat forecasts as more companies are buying the fuck out of whatever ORCL software does and that can only be positive, unless Oracle software is responsible for promoting Paris Hilton's album, the intelligent design theory, or trickle-down economics.
In macro news, German business confidence rose as the Business Climate Index predicted the climate is getting so much better that all rain showers will now be golden. The index managed to rise to a whopping 94.7, beating out expectations of 94.5 and we all know how great a .2 beat is of a number with no context, right? Actually, the number comes from a survey of 7,000 German firms across their biggest industries including manufacturing, construction, wholesaling, retailing, and scat film shooting. The longterm average is 96 so I guess everything in Europe is almost back to normal, just don't tell the Greeks.
And finally Money McBags favorite RICK met expectations and didn't give guidance but said the current $.19 quarterly eps is a decent range though the first two quarters this year should be stronger than that with the NBA all-star game in Dallas and the Super Bowl and Pro Bowl in Miami (no seriously, they said that). Unfortunately, no one on the call asked how revenues during the Super Bowl will be effected by Chris Henry's absence and Pac Man Jones' unemployment.
If you read the transcript from their call, which I highly recommend even though it's no Tolstoy (but it is an asshair better than any of that Dan Brown crap), you can even learn of RICK's successful recent Toys for Tots event in their NYC club and no, Money McBags is not making that up but yes he is pissed his parents never got him those kind of toys when he was a tot. The point is, this company is easily going to earn $.76 next year and is likely going to earn over $1.00 (where analyst estimates currently are). They are trading at ~10x a worse case scenario and 6x-7x a more reasonable estimate. The problem is that RICK's is always one hummer in the champagne room away from being screwed (pun intended) so Money McBags recommends you go long RICK and buy some long dated out of the money puts to cover your ass should that happen (though he also recommends that RICK employees do everything but cover their asses).

Enjoy the weekend.
Thursday, December 10, 2009
12/10/09 Midday Report: Take our cheap shit, please
The market is off to the races again as a rise in US exports turned on the cold water and created some shrinkage to the US trade deficit. The trade deficit dropped by 7% which was better than expectations of a rising deficit (and I know, it is hard to believe expectations were wrong much like it is hard to believe printing money will lead to inflation, but let's all just take deep breaths and try to move on from this).
So basically, with a weakened dollar, the US is becoming China without the lead paint and bad drivers (As an aside, the Chinese are forecast to buy more cars in 2010 than Americans, so now would be a good time to buy that auto body shop in Shanghai) as we can make much cheaper crap that other countries want to purchase. This isn't a bad thing as any sales are better than no sales, and if it can create demand and jobs then we'll have some people no longer sucking on the teet of good ole Uncle Sam (and hopefully earning enough money to suck on the teet of good ole Aunt Sam). So as long as people don't want to travel out of the country since the dollar can now only buy about fifteen minutes in an Amsterdam motel room and a half a croissant, this is decent news.
As far as jobs, the average number of Americans filing first-time jobless claims over the past four weeks fell to a one-year low and the number of newly laid-off workers seeking jobless benefits rose more than expected last week and were higher than expectations. So it fell to a one-year low and it rose in the same week. That's a neat fucking trick. Next up, jobless claims will prove that 2+2 does not always equal 4 (in honor of the Underground Man), will walk and chew gum at the same time, and will create a building to scale based on MC Escher's blueprints. The point is, depending on which news source you read (one is using an average 4 week number, and I assume one just using last week's number), we're either still fucked or a bit less fucked, yet definitely totally confused.
In the market, C thinks they are going to raise $15B-$20B to pay back their TARP funds (and honestly, I would rather burn money and dip my balls in the searing hot ashes than buy any securities offering from C, so good luck with that) and RIMM is creating jobs by launching in China which has the stock moving up.
There's still a bunch of noise as the economy tries to figure out just how stimulated it is (it has had its GDP tickled and been shown pictures of some hot growing economies, but it may also need an insertion in it's back door lending policies), so be careful out there.
So basically, with a weakened dollar, the US is becoming China without the lead paint and bad drivers (As an aside, the Chinese are forecast to buy more cars in 2010 than Americans, so now would be a good time to buy that auto body shop in Shanghai) as we can make much cheaper crap that other countries want to purchase. This isn't a bad thing as any sales are better than no sales, and if it can create demand and jobs then we'll have some people no longer sucking on the teet of good ole Uncle Sam (and hopefully earning enough money to suck on the teet of good ole Aunt Sam). So as long as people don't want to travel out of the country since the dollar can now only buy about fifteen minutes in an Amsterdam motel room and a half a croissant, this is decent news.

As far as jobs, the average number of Americans filing first-time jobless claims over the past four weeks fell to a one-year low and the number of newly laid-off workers seeking jobless benefits rose more than expected last week and were higher than expectations. So it fell to a one-year low and it rose in the same week. That's a neat fucking trick. Next up, jobless claims will prove that 2+2 does not always equal 4 (in honor of the Underground Man), will walk and chew gum at the same time, and will create a building to scale based on MC Escher's blueprints. The point is, depending on which news source you read (one is using an average 4 week number, and I assume one just using last week's number), we're either still fucked or a bit less fucked, yet definitely totally confused.

In the market, C thinks they are going to raise $15B-$20B to pay back their TARP funds (and honestly, I would rather burn money and dip my balls in the searing hot ashes than buy any securities offering from C, so good luck with that) and RIMM is creating jobs by launching in China which has the stock moving up.
There's still a bunch of noise as the economy tries to figure out just how stimulated it is (it has had its GDP tickled and been shown pictures of some hot growing economies, but it may also need an insertion in it's back door lending policies), so be careful out there.
Subscribe to:
Posts (Atom)