The market ran faster today than Roman Polanski going to get his keys to pick the baby sitter up because the manufacturing sector grew at its slowest pace since December, private construction spend dipped for the second month in a row, and Ben Bernanke said shit still sucks out there. So rally fucking on like Donkey Kong having his way with the princess, only if the princess had tainted his banana wth AIDS.
With the market rallying on macro news that was about as positive as a RuPaul pregnancy test, Money McBags is left to wonder what he is missing, how much the market would rally if there were actually something positive going on in the economy (like maybe either the second derivative of released data positively increasing or the unemployment rate decreasing and not from just from a declining labor force participation rate), and how he overlooked this delightful NSFW Alice Eve scene which has caused his Oscar to stand and applaud. Money McBags is not quite sure how to interpret the market moving in opposition to macro data, as the language of giberrish wasn't on the rosetta stone the last time he checked, but he hopes those of you buying in to this capitualting market are careful.
As for macro news, Benny B warned us that "we have a considerable way to go to achieve full recovery in our economy, and many Americans are still grappling with unemployment, foreclosure, and lost savings, in addition to the angst and nausea they feel every time they look at the deficit and realize their kids may be more fucked than Stephen Hawking in a duel." Ok, perhaps that last bit was made up but, whatever. Bennie B did get slightly positive by saying he fully expects consumer spend to pick up in the next few quarters as wages rise, business demand picks up, and the US finally figures out what to do with all of the underwear they stole.
Money McBags is a bit skeptical of Bennie B's claims since unemployment remains more stagnant than the Terri Moulton Horman for "Stepmother of the Year" campaign or jokes here on the great When Genius Prevailed so it's not clear where these rising wages are going to come from unless it's from laying more people off and then giving those still employed a bit of the saved salary, which of course would do nothing for overall consumer demand. But hey, when Bennie B gets his Fed on, the market listens (to the parts it wants to hear).
In other macro news, the ISM came out with their numbers for July and the manufacturing sector grew at its slowest pace this year, but luckily, the 55.5 number was better than the 54.2 analyst had guessed so rally on my friends. It was the third straight month (and the month was so straight it even got it up for a Kathy Najimy-Rachel Ray threesome) of slower growth but remember, readings above 50 still signal expansion, so apparently there is nothing to see here (except for new orders dropping to their lowest level in over a year, production slowing down, and Kagney Linn Karter).
In the final bit of macro news, construction spending rose .1% as increased investment in public projects (perhaps maybe a bridge to somewhere) offset the 15th straight monthly decline in private nonresidential construction and the .8% decline in private homebuilding (which included growth from the Greenspanville's being erected across the country, and yes, Money McBags said erected). Yowsa. As usual, last month's new construction was revised downward from a .2% drop to a 1% drop as part of the government's "hold the shock and hope for no awe" strategy, so this month's .1% decline should be labeled as "wishful thinking."
Internationally, China's manufacturing sector cooled further as the government tries to reign in reckless speculation on real estate and ben wa balls. The official purchasing managers' index fell to a 17 month low of 51.2 from 52.1, a separate PMI released today by HSBC and Markit Economics showed a drop to 49.4 from 50.4, and a third reading of PMI from the desk of Sum Dum Gai simply took the average of the two. China's ec0nomy slowing down is actually favorable as it has been growing at a rate less sustainable than a conversation involving only eye contact with Christina Hendricks so having it moderate a bit and perhaps not inflate to a bubble like every other emerged economy would be beneficial for all involved.
Driving the market today was the European banking sector thanks to HSBC putting down its fag, rolling up its sleves, and earning the fuck out of some profits. The bank doubled its profits to $7B despite revenue growth declining by 7%, operating expenses increasing by 9%, and no one having any fucking money. Profits rose as losses on bad loans tumbled to $7.5B, just over half of last year's losses, and were the result of bad loans rolling off the books and the bank not lending anyone any money. BNP Paribas also put up a good Q, with the French bank's profits rising due to credit getting better and having Laetita Casta on call to help coax out customer deposits. Just like in the US, bank profitablity seems to be rising across the globe despite declining revenues as credit is improving. That said, credit can only drive earnings for so long until the banks are going to have to start lending to people again to drive revenue and thus the vicious cycle will begin anew.
In other market news, Blackberry is not just losing market share to the iPhone but now the UAE said they will cut RIMM's data service like the dirty infidel that it is. The UAE cited security concerns over RIMM's reliance on encrypted emails which make it easier for criminals to operate and harder for the government to watch that stupid fucking video of the double rainbow that everyone seems to be emailing around. Not since Peter Chung anointed himself King has there been an international email controversy like this and it does not augur well for RIMM's jobs overseas going forward as other countries like Saudi Arabia are also thinking about taking steps to ban Blackberry's mobile services.
Finally, KO got an upgrade today from JP Morgan on the strength of the company's emerging markets and having read Money McBags' columns about the solid brand equity overseas the company enjoys. An article in Baron's also pimped KO today, saying it could rise by at least 10% in the next year because of North American markets and because it still tastes better than water. And last but not least, Corning was up nearly 6% on news that it's 50 year old Gorilla glass could be the next bazillion dollar product for flat screens and touch screens as it is 2 to 3 times stronger than regular glass, half the thickness, and sells for only a few bananas. The lighter, sturdier glass should cut down on shipping costs and scratched screens while also being easier to clean after one gets done with a chat roulette session.
In small cap news, everything was up. Money McBags is short on time today but he wants to highlight KIRK which remains too fucking cheap even though it was up strong today. Money McBags broke KIRK down a little over month ago saying its low end market focus (midwestern/southeastern housewives who love tchotchkes more than Joanie loves Chachi), growth through the downturn (and now they are going to be opening stores instead of closing them), and valuation (it is now trading ~9x to 10x eps estimates not including the $3.50 per share of cash on the balance sheet) make it almost as attractive as Diora Baird, and nothing has changed since then except for John Kyl's stand on the 14th Amendment. The other interesting small cap name is NTRI who traded down big on Friday after what Money McBags thought was an OKish quarter. He has to go through it in more detail and while he wouldn't be a buyer of the stock until their management team actually performs (they are 0 for the last bazillion quarters, rounding up to the nearest bazillion), they pay a nice yield, have a terrific cost structure, and are in a growing (pun intended) market. It's worth keeping on a watch list for when/if they can figure out how to start accelerating their growth rates (Money McBags votes for getting Nicole Eggert as a spokeswoman, but that's just him).
Showing posts with label Bernanke. Show all posts
Showing posts with label Bernanke. Show all posts
Monday, August 2, 2010


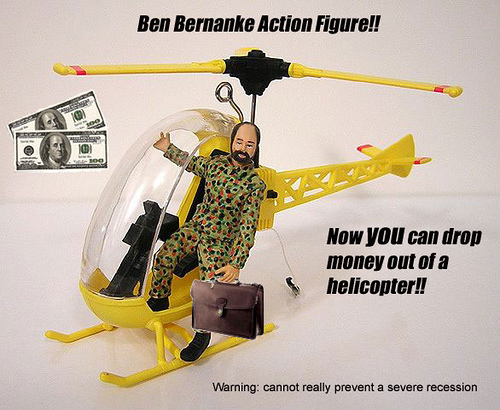


Wednesday, July 21, 2010
7/21/10 Midevening Report: Market "unusually certain" that it should go down
The market was chugging right along today like a Kennedy at a sorority mixer after Apple titillated the market with sales stronger than the breath of either of the world's foremost cunning linguists, the great Vladmir Nabokov and the greater Janine Lindemulder, until Ben Bernanke got up and threw his figurative Baby Ruth into the market's pool causing investors to run for safety. Bennie B. got his best gangsta lean on and told the Senate Banking Committee, who never met a bubble they couldn't regulate after it had already deflated itself, that the recovery remains "unusually uncertain and shit" before repeatedly rhetorically axing "you know what I mean?" His befuddling remarks caused the market to fall faster than Andrew Johnson's reputation in the Republican party after suceeding (or more appropriately, failing) Lincoln and thus negated a rare day where earnings were mostly positive.
While it's not entirely clear what "unusually uncertain" means, especially since Money McBags finds all uncertainties a bit unusual, he believes the term is Fed-bonics for "We have less of a fucking clue about what is happening than we usually do." Bernanke did say the Fed is ready to step in as needed and while he didn't say what those steps may be, one can assume they include keeping rates low (for an extended period like a metrorrhagia sufferer), manipulating the Fed's balance sheet, and the Charleston.
Prior to Bennie B. unleashing his pimp hand and treating the market like his bottom bitch, President Obama signed the financial legislation bill which after two years of debate has been watered down more than a virgin bloody mary without the tomato juice or tobasco (though he signed it "Alan Smithee", so it's not clear if the bill will hold). The most worrisome part of the bill is that many of the details are more open ended than Alexis Texas right before filming Buttwoman which leaves regulators plenty of wiggle room to fuck more shit up. As far as Money McBags is concerned the bill didn't go far enough in regulating the use of derivatives, in limiting the size of banks, or in raising reserve requirements and making banks responsible for their greed which led to credit scoring models to be less frequently used than MySpace (does anyone remember that piece of crap?).
In macro news, mortgage applications jumped last week for the first time in five weeks in what surely is a fictitious number, or a typo. What is more believable is that refi applications were at 14 month highs as record low mortgage rates of 4.59% have led homeowners to lower their interest payments faster than the Stoughton, MA police department lowered the boom on one of their officers who was just doing a little (and Money McBags stresses "little") due diligence.
The real story of the day (other than Bennie B.'s uncertain uncertainty) was Apple's Q in which they sold what is known in the retail space as "a fuckload of shit" and put up a huge earnings number. Apple's net income rose by 78% by selling 3.3MM iPads, 8.4MM iPhones despite people waiting until the end of the Q for the iPhone 4 launch in order to be able to make use of the front facing camera while masturbating for strangers on chatroulette from work bathroom stalls everywhere, and a whopping and quarterly high 3.5MM Macintosh computers making everyone loudly say "Apple sells computers?" Revenue was up 60% to $15.7B, beating analyst guesses by $1B, and putting the company only $4B away from world domination. Steve Jobs also defended the iPhone antenna problem by simply saying "deal with it. And if you don't like it, go by one of those Blackberries and make sure it matches your 8-track player and Jams." That said, Lenovo is set to launch a challenger to the iPad using GOOG's Android system and they are referring to it as "LePad" because apparently "LeThingThatIsn'tGoingToSell" was already taken.
In other strong earnings news, MS put up a ginormous Q, harkening back to the pre-2006 days when investment banks ruled the markets like Jessica Simpson ruled the short bus in her elementary school days. Revenue grew 53% to $7.95B and beat analyst guesses of $7.93B driven by MS' trading business which earned $4.1B in operating profits after trading their souls for three more months of manipulating the markets and a good night kiss from Rose Huntington Whiteley. Also, KO put up a good quarter on the heels of PEP's outperformance yesteray once again reinforcing the demand inelasticity of sugar and water. KO earned $1.06 per share, beating analyst guesses of $1.03 per share, and saw 5% growth worldwide led by international growth ex. Europe of 6%. Money McBags is a longterm owner of KO because it is a cheap aspirational brand that appeals to emerging markets that will continue to grow as the US slogs its way towards mediocrity (though mediocrity would be a good thing). Finally, YHOO dropped 8% on a disappointing earnings report as revenue growth remains more challenging than Sudoku for a dyslexia sufferer.
In small cap news, Money McBags mentioned CRUS yesterday but he was in such a time rush that he missed their quarterly earnings release from earlier in the day which turned out to be more positive than Robin Williams' herpes test. The company earned $.29 per share in the quarter on 118% y/y revenue growth and margins going to 57% from 52% last year and 56% last Q. Most surprisingly, their energy business jumped up to $28MM from $22MM as a result of the both the power meter business and their energy exploration business. On the call, they talked about this business but gave fewer useful details as to what is driving it than a republican strategist gives details about their plan to fix the economy.
That said, it's really CRUS' consumer audio business that has investors drooling over this company as if it were Hayley Atwell as they provide an audio chip for the iPhone and that segment absolutely killed it. Revenue was up 32% sequentially in that segment with Apple moving to 35% of their overall revenues. Company guidance was also stellar with next Q predicted to have at the midpoints $102MM in revenues, 57% gross margins, and $27MM non-Gaap op ex. and while Money McBags is no maffematecian (he only counts to two when told to turn his head and cough), those number should get them to ~$.44 eps as they still have more NOLs than Money McBags has broken dreams.
The hard part is forecasting this company since they are obviously a play on the iPhone and AAPL could find a new suplier or put more pricing pressure on them at any time. Now look, Money McBags doesn't think that will happen anytime soon as their chip is supposed to provide the best audio quality and they are continually investing in R&D, but it is something of which investors should be aware. Money McBags' previous estimate for fiscal year EPS was $1.20 but with CRUS earning $.29 per share in Q1 and guiding for $.44 per share in Q2, $1.20 seems like it is lower than Andy Rooney's balls. So Money McBags is going to get a bit conservative here and estimate that the energy business falls to ~$24MM quarterly run rate, the non-AAPL consumer business stays flat, and the AAPL business only grows 10% sequentially.
Doing that (and using 55% margins which may be on the low end and $110MM op ex), Money McBags gets an estimate of $1.47 which is about double what they should earn in the first half of the fiscal year. Of course, those are very low end estimates as the AAPL business has been growing 30%+ sequentially and gross margins have been above 55%, so at the hgh end we could be looking at closer to $1.70 EPS for the fiscal year.
Either way, the stock is now trading at ~$19 which is ~13x Money McBags' low end estimate and the company has ~$2.50 in cash on the balance sheet and 13x for a company growing this fast is just way too fucking cheap. If you want, throw a 20x on $1.47 and get to ~$30 for a target price. As long as Apple doesn't pull the rug out from under these guys, there is plenty of room to move up even though it has already had a better run than a roidal Ben Johnson.


While it's not entirely clear what "unusually uncertain" means, especially since Money McBags finds all uncertainties a bit unusual, he believes the term is Fed-bonics for "We have less of a fucking clue about what is happening than we usually do." Bernanke did say the Fed is ready to step in as needed and while he didn't say what those steps may be, one can assume they include keeping rates low (for an extended period like a metrorrhagia sufferer), manipulating the Fed's balance sheet, and the Charleston.
Prior to Bennie B. unleashing his pimp hand and treating the market like his bottom bitch, President Obama signed the financial legislation bill which after two years of debate has been watered down more than a virgin bloody mary without the tomato juice or tobasco (though he signed it "Alan Smithee", so it's not clear if the bill will hold). The most worrisome part of the bill is that many of the details are more open ended than Alexis Texas right before filming Buttwoman which leaves regulators plenty of wiggle room to fuck more shit up. As far as Money McBags is concerned the bill didn't go far enough in regulating the use of derivatives, in limiting the size of banks, or in raising reserve requirements and making banks responsible for their greed which led to credit scoring models to be less frequently used than MySpace (does anyone remember that piece of crap?).

In macro news, mortgage applications jumped last week for the first time in five weeks in what surely is a fictitious number, or a typo. What is more believable is that refi applications were at 14 month highs as record low mortgage rates of 4.59% have led homeowners to lower their interest payments faster than the Stoughton, MA police department lowered the boom on one of their officers who was just doing a little (and Money McBags stresses "little") due diligence.
The real story of the day (other than Bennie B.'s uncertain uncertainty) was Apple's Q in which they sold what is known in the retail space as "a fuckload of shit" and put up a huge earnings number. Apple's net income rose by 78% by selling 3.3MM iPads, 8.4MM iPhones despite people waiting until the end of the Q for the iPhone 4 launch in order to be able to make use of the front facing camera while masturbating for strangers on chatroulette from work bathroom stalls everywhere, and a whopping and quarterly high 3.5MM Macintosh computers making everyone loudly say "Apple sells computers?" Revenue was up 60% to $15.7B, beating analyst guesses by $1B, and putting the company only $4B away from world domination. Steve Jobs also defended the iPhone antenna problem by simply saying "deal with it. And if you don't like it, go by one of those Blackberries and make sure it matches your 8-track player and Jams." That said, Lenovo is set to launch a challenger to the iPad using GOOG's Android system and they are referring to it as "LePad" because apparently "LeThingThatIsn'tGoingToSell" was already taken.

In other strong earnings news, MS put up a ginormous Q, harkening back to the pre-2006 days when investment banks ruled the markets like Jessica Simpson ruled the short bus in her elementary school days. Revenue grew 53% to $7.95B and beat analyst guesses of $7.93B driven by MS' trading business which earned $4.1B in operating profits after trading their souls for three more months of manipulating the markets and a good night kiss from Rose Huntington Whiteley. Also, KO put up a good quarter on the heels of PEP's outperformance yesteray once again reinforcing the demand inelasticity of sugar and water. KO earned $1.06 per share, beating analyst guesses of $1.03 per share, and saw 5% growth worldwide led by international growth ex. Europe of 6%. Money McBags is a longterm owner of KO because it is a cheap aspirational brand that appeals to emerging markets that will continue to grow as the US slogs its way towards mediocrity (though mediocrity would be a good thing). Finally, YHOO dropped 8% on a disappointing earnings report as revenue growth remains more challenging than Sudoku for a dyslexia sufferer.


In small cap news, Money McBags mentioned CRUS yesterday but he was in such a time rush that he missed their quarterly earnings release from earlier in the day which turned out to be more positive than Robin Williams' herpes test. The company earned $.29 per share in the quarter on 118% y/y revenue growth and margins going to 57% from 52% last year and 56% last Q. Most surprisingly, their energy business jumped up to $28MM from $22MM as a result of the both the power meter business and their energy exploration business. On the call, they talked about this business but gave fewer useful details as to what is driving it than a republican strategist gives details about their plan to fix the economy.
That said, it's really CRUS' consumer audio business that has investors drooling over this company as if it were Hayley Atwell as they provide an audio chip for the iPhone and that segment absolutely killed it. Revenue was up 32% sequentially in that segment with Apple moving to 35% of their overall revenues. Company guidance was also stellar with next Q predicted to have at the midpoints $102MM in revenues, 57% gross margins, and $27MM non-Gaap op ex. and while Money McBags is no maffematecian (he only counts to two when told to turn his head and cough), those number should get them to ~$.44 eps as they still have more NOLs than Money McBags has broken dreams.

The hard part is forecasting this company since they are obviously a play on the iPhone and AAPL could find a new suplier or put more pricing pressure on them at any time. Now look, Money McBags doesn't think that will happen anytime soon as their chip is supposed to provide the best audio quality and they are continually investing in R&D, but it is something of which investors should be aware. Money McBags' previous estimate for fiscal year EPS was $1.20 but with CRUS earning $.29 per share in Q1 and guiding for $.44 per share in Q2, $1.20 seems like it is lower than Andy Rooney's balls. So Money McBags is going to get a bit conservative here and estimate that the energy business falls to ~$24MM quarterly run rate, the non-AAPL consumer business stays flat, and the AAPL business only grows 10% sequentially.
Doing that (and using 55% margins which may be on the low end and $110MM op ex), Money McBags gets an estimate of $1.47 which is about double what they should earn in the first half of the fiscal year. Of course, those are very low end estimates as the AAPL business has been growing 30%+ sequentially and gross margins have been above 55%, so at the hgh end we could be looking at closer to $1.70 EPS for the fiscal year.
Either way, the stock is now trading at ~$19 which is ~13x Money McBags' low end estimate and the company has ~$2.50 in cash on the balance sheet and 13x for a company growing this fast is just way too fucking cheap. If you want, throw a 20x on $1.47 and get to ~$30 for a target price. As long as Apple doesn't pull the rug out from under these guys, there is plenty of room to move up even though it has already had a better run than a roidal Ben Johnson.

Tuesday, June 8, 2010
6/8/10 Midevening Report: Bernanke speech fails to significantly rally the market, says he'll overpromise more next time
The market was relatively quiet today as there was a lack of macro news though Fed Chairman Ben Bernanke was out late Monday saying: "My best guess is that we’ll have a continued recovery, but it won’t feel terrific like a blumpkin from Sara Varone followed by a nice wipe with that oh so soft aloe infused Cottonelle. Instead, it will feel more like having your nut hairs pulled out while listening to the smooth adult contemporary sounds of Sade". Ok, Money McBags made part of that up but that's not the point, the point is, Bernanke is hedging on this recovery like he just bought FAZ in his IRA. While he says the economy won't likely have a double dip recession, he did not say it wouldn't have a single dip recession followed by a falling off the cliff depression, so it's merely a matter of semantics. Bernanke also dusted off his Phillips curve (though it wasn't as curvy as Kimberly Phillips) and added that the central bank would raise rates before the economy returns to full employment, which should be any century now. That's great, but Money McBags would like to know what the full employment rate is? Is it 4%, 6%, or whatever proof the whiskey was that Milton Friedman was drinking when he came up with NAIRU (seriously Milt, you couldn't have come up with a catchier name than the Non-Accelerating Inflation Rate of Unemployment? Really? That name could put Ritalin out of business because just reading it has to make even the most hyperactive person drowsy.)? The point is, the full employment rate is a bogus hurdle as there is no set rate so saying rates will rise before we reach that level is as helpful as saying you'll stop running when you catch the horizon. With the stimulus funds coming to an end over the next few quarters and the economy already starting to show signs of coming down from its stimulus induced bender where it got drunk off of bail outs and hand outs and now finds itself waking up in a pool of its own spending while dry humping Greece's Aegean coast to the sweet whisperings of Benjamin S. Bernanke and and his magical money making machine, the economy is in a precarious position (though not as precarious of a position as Kirstie Alley's girdle).
Internationally, the new government in Hungary has announced a set of austerity measures aimed at solving their debt crisis. The austerity measures include cutting public wages, overhauling the tax system, banning mortgage lending in foreign currencies, and stopping free cookie day at the National Assembly. Also, the European Union's finance ministers met in Luxembourg with the most important outcomes being an agreement to allow tighter oversight on countries suspected of falsifying economic data and an agreement that Ginger Spice was the hottest of the Spice Girls.
In stock news, AAPL introduced a $199 iPhone which has a front facing camera that should now allow users to masturbate on chatroulette wherever they may be. The new iPhone is slimmer than the previous version, has better picture quality, and doesn't insist on cuddling when you are done with it. In other stock news, MCD had better than guessed at growth for the month of May of 4.8% worldwide thanks to the fact that they sell cheap shit and people can only afford to eat cheap shit. The company announced the falling Euro would impact yearly earnings but announced that to make up for those lost earning they are forming a partnership with American Heart Association to get a portion of the profits from all angiograms caused by eating their food. Finally, analysts were busy today with INTC downgraded by SIG to neutral because the analyst had to do something to try to drum up trading business for SIG and Dick Bove, who never saw a financial stock he didn't like and didn't understand, cut his price target at JP Morgan from jizztastic to just ballticklingly good.
In small cap stocks, Money McBags favorite KITD continues to get pounded like Alexis Texas on payday. With ~70% of their revenues coming from Europe, topline should be impacted by the 15%-20% drop in the Euro with investors seemingly betting on worse. Given that, it is difficult to come up with a short term valuation for KITD as the Euro appears to be falling off worse than proper grammar or Britney Spears' top. Last Q, the $/Euro exchange rate was somewhere around $1.38 and this Q, it's likely going to be around $1.25, and after that, who knows? So lets take a worse case scenario where we assume the exchange goes to parity. So that would be a 28% drop in the exchange rate from last Q. Money McBags thinks at the high end KITD can do $150MM of revenue next year, but let's call it $130MM because of the global uncertainty. The thing is, that number was derived off of the old $/EU exchange so if we knock 70% of their revenue (their EU exposed revenue) by 28%, revenue decreases by ~$25MM. So insted of $130MM, a worst case scenario yields revenue of $105MM and at 20% EBITDA margins, that is ~$21MM EBITDA. The company currently has a market cap of $210MM but they have somewhere around $30MM in cash after their last deal so they have an enterprise value of roughly $180MM and thus are currently at a worst case scenario of ~9x EV/EBITDA and topline growth in that scenario would still be ~20% (and dollar euro parity is almost as bad a scenario for the financial markets as having your daughter bring home Jordan Van Der Sloot for Thanksgiving Break). Of course all of this assumes that their costs and revenue are tied together so if the euro drops by 28% the associated costs with that will drop by 28% and thus margins will remain intact. The point is, Money McBags still likes this company longterm as they are in a rapidly growing space that is going to continue to grow for several years, but there are certainly short term currency issues. However, they are diversifying their revenues in to the US and Asia so as to become less dependent on Europe so while things look bad now, in the long run this company should be fine. With uncertainty comes opportunity and it is getting to the point where this company is just getting stupid cheap.


Internationally, the new government in Hungary has announced a set of austerity measures aimed at solving their debt crisis. The austerity measures include cutting public wages, overhauling the tax system, banning mortgage lending in foreign currencies, and stopping free cookie day at the National Assembly. Also, the European Union's finance ministers met in Luxembourg with the most important outcomes being an agreement to allow tighter oversight on countries suspected of falsifying economic data and an agreement that Ginger Spice was the hottest of the Spice Girls.

In stock news, AAPL introduced a $199 iPhone which has a front facing camera that should now allow users to masturbate on chatroulette wherever they may be. The new iPhone is slimmer than the previous version, has better picture quality, and doesn't insist on cuddling when you are done with it. In other stock news, MCD had better than guessed at growth for the month of May of 4.8% worldwide thanks to the fact that they sell cheap shit and people can only afford to eat cheap shit. The company announced the falling Euro would impact yearly earnings but announced that to make up for those lost earning they are forming a partnership with American Heart Association to get a portion of the profits from all angiograms caused by eating their food. Finally, analysts were busy today with INTC downgraded by SIG to neutral because the analyst had to do something to try to drum up trading business for SIG and Dick Bove, who never saw a financial stock he didn't like and didn't understand, cut his price target at JP Morgan from jizztastic to just ballticklingly good.
In small cap stocks, Money McBags favorite KITD continues to get pounded like Alexis Texas on payday. With ~70% of their revenues coming from Europe, topline should be impacted by the 15%-20% drop in the Euro with investors seemingly betting on worse. Given that, it is difficult to come up with a short term valuation for KITD as the Euro appears to be falling off worse than proper grammar or Britney Spears' top. Last Q, the $/Euro exchange rate was somewhere around $1.38 and this Q, it's likely going to be around $1.25, and after that, who knows? So lets take a worse case scenario where we assume the exchange goes to parity. So that would be a 28% drop in the exchange rate from last Q. Money McBags thinks at the high end KITD can do $150MM of revenue next year, but let's call it $130MM because of the global uncertainty. The thing is, that number was derived off of the old $/EU exchange so if we knock 70% of their revenue (their EU exposed revenue) by 28%, revenue decreases by ~$25MM. So insted of $130MM, a worst case scenario yields revenue of $105MM and at 20% EBITDA margins, that is ~$21MM EBITDA. The company currently has a market cap of $210MM but they have somewhere around $30MM in cash after their last deal so they have an enterprise value of roughly $180MM and thus are currently at a worst case scenario of ~9x EV/EBITDA and topline growth in that scenario would still be ~20% (and dollar euro parity is almost as bad a scenario for the financial markets as having your daughter bring home Jordan Van Der Sloot for Thanksgiving Break). Of course all of this assumes that their costs and revenue are tied together so if the euro drops by 28% the associated costs with that will drop by 28% and thus margins will remain intact. The point is, Money McBags still likes this company longterm as they are in a rapidly growing space that is going to continue to grow for several years, but there are certainly short term currency issues. However, they are diversifying their revenues in to the US and Asia so as to become less dependent on Europe so while things look bad now, in the long run this company should be fine. With uncertainty comes opportunity and it is getting to the point where this company is just getting stupid cheap.

Wednesday, April 14, 2010
4/14/10 Midafternoon Report: Market movin' on up, only a matter of time before it buys a dee-luxe apartment in the sky
Oh shit, it is on today like fucking Donkey Kong only this time Mario is not only going to save the Princess but he's going to get rich while doing so. The market is rallying like it's 1999 with positive earnings, positive macro data, and not a fucking peep out of those Greek assholes who keep trying to fuck things up by going bankrupt (You hear that Greece? Stay the fuck away from the market, put your hands on the car, and assume the position). On the day before tax day, the market is making investors forget about the dough they are handing over to Uncle Sam and instead focusing them on the dough they will have to hand over to Uncle Sam next year with all of their oh so sweet gains. Ahh, to be young and invested. The rally today was sparked by earnings from JPM and INTC who treated earnings like it was a cup and they were the two girls (and if you don't get that reference and have a very strong stomach and lenient internet rules, Money McBags begrudgingly recommends you google "two girls one cup," but don't say he didn't warn you). Along with positive earnings, macro data was so good Ben Bernanke was seen taking it out to lunch, playing a little footsie with it under the table, and then inviting it back to his hotel for a little regression analysis to make sure it was heteroskedastic.
US retail sales were up 1.6% in March over the previous month and up 7.4% from March of 2009 which beat economists' guesses. The beat was driven by car sales which were up 6.8% thanks to incentives such as tax breaks, low financing, and taint massages by Kelly Brook. Even with unemployment stuck at 9.7% like Keely Shaye Smith in a mudslide, consumers are spending because that is what they do. When the AIDS scare hit the porn scene in the 1980s, did that stop great films from being made? Maybe for a bit but now 20+ years later we're back to bareback ATM films with no worries by the performers about diseases. This is just like consumers coming back after the recession and levering up again because daddy needs his 60 inch tv. People have short memories (and Money McBags' short memories are mostly of He Ping Ping) and are generally optimistic so good news spurs them to repeat behaviors that may not be optimal for them in the long run. In other macro news, the CPI was up only.1% and was flat excluding food and energy (or you know, the things you actually need). The lack of an increase in CPI bodes well for the Federal Reserves' plan to keep interest rates low for an "extended period" as inflation looks like it will be pushed out for another few quarters until investors can actually finish counting all of the cash the US government printed (you all remember Money McBags' "Too big to count" hypothesis). The one small turd in the punchbowl today was that mortgage applications fell for the second straight week as people seem content to live in their current abodes and the game of flipping houses has finally passed like a painful kidney stone, Mickey Roarke's comeback, or one piece bathing suits.
On top of the good macro news, Bernanke was getting his Fed on today in front of Congress by saying that he doesn't plan to change any policy decisions but the recovery may be moderate due to high and prolonged unemployment, low construction demand, the poor fiscal condition of state and local governments, and Rasheed Wallace. Bernanke was quoted as saying about borrowing that "The decline in large part reflects sluggish loan demand and the fact that many potential borrowers no longer qualify for credit, both results of a weak economy." Luckily, banks have shorter memories than investors and it is only a matter of months before FICO 560 people are once again getting $500k loans to buy houses in states they don't work at variable interest rates. But hey, until then, rally on!!!!!!!
In stock news, JP Morgan beat estimates, grew income by 55%, and raised their outlook for the year. So fuck you right in the ear recession, you hear that (though maybe you won't hear it with a dick in your ear)? JPM earned $.74 per share which was $.10 above analyst guesses and revenue was $28.2B, ~$2B above guesses of $26.5B. While JPM's retail bank and customer card businesses are still struggling a bit, the investment bank blew it out thanks to strong fixed income trading. And if a weak retail business and strong fixed income trading don't bode well for the economy, then Money McBags didn't learn anything over these past few years. Oh wait, trading profits and a fuckshit consumer are exactly what got us in to this situation, ugh. But I guess there is something to say about the classics. CEO Jamie Dimon did say that “We continued to see delinquencies stabilize, and in some cases improve, in our credit portfolios,” which is a good sign, but then he added "and if they don't stabilize, we'll just create some complex products to trade with other banks and further boost our illusory profits." While Chase card may have struggled, at least the bad loans have been siphoned off into a holding company to separate the risk and to hopefully make investors forget about what happened and just concentrate on Chase's growth portfolio which won't need to be put in to it's own holding tank, until it does. In other stock news INTC crushed their quarter with eps coming in at $.43 which was well above last year's $.11 eps and revenue was up $3B to $10B. They also announced strong revenue guidance, an improving gross margin, and they will be hiring 1k to 2k people which will be their first new hires in 5 years, so take that unemployment rate. INTC's Q was so good that Money McBags may have to take it in to the bathroom and have a little time for himself with it while thinking about INTC's motherboards which are so sexy they can be considered MBILFs. Finally Apple announced that they are going to delay the iPad launch outside of the US because demand in the US has been stronger than the demand for accutane in Jessica Simpson's house or the female condom in Britney Spears' house.
In small cap news, AAPL's strong demand for the iPad could bode well for CRUS if CRUS actually has a chip in the iPad like they do the iPhone. The stock is reacting well today to the INTC blow out quarter and potentially the iPad news. Money McBags thinks they can earn $.73 next year but assumes only 12% topline growth so if their energy business can continue to come back and if their audio business just slows down a little from their current 80% growth rate, that number should be surpassed easier than a 3rd grader surpasses Kim Kardashian's reading level. The stock is now near $10, and remember Money McBags has been talking about CRUS since 1/12/10 when it was trading just under $8 and he mentioned he bought some on 1/29/10 when it had fallen below $7, so a >40% gain in 2+ months isn't too bad. Money McBags hopes you all joined him on this ride and have been able to take your lady friends (or man friends) out to many lobster tail and bj dinners. That said, they have $2 in cash so they are really trading at ~10x Money McBags admittedly cautious estimate for this year which is pretty fucking cheap for a company that sells a chip to the biggest fucking electronics seller/fad in the Universe. Also, JOEZ is rallying today after the huge sell off from their earnings. Money McBags is still on the sidelines here for reasons he has laid out over the past few days. Basically, if you're in the market today you can't lose, like flipping a two headed coin, having your brother be the Governor of the state you need to win in a contested election, or being Alexis Texas in a great ass contest. One stock that is down which Money McBags is going to start looking in to again is CKSW which produces the best logistics/scheduling software for fleets. The company announced a 15MM share shelf offering today which is really fucking odd since they only have 30MM shares outstanding so this would be hella dilutive if they actually went through with the full offering. Money McBags is going to look more in to this over the next few days as the company apparently has the best software, but a shelf like that is more perplexing than Jennifer Love Hewitt's career or an Amish computer camp.
US retail sales were up 1.6% in March over the previous month and up 7.4% from March of 2009 which beat economists' guesses. The beat was driven by car sales which were up 6.8% thanks to incentives such as tax breaks, low financing, and taint massages by Kelly Brook. Even with unemployment stuck at 9.7% like Keely Shaye Smith in a mudslide, consumers are spending because that is what they do. When the AIDS scare hit the porn scene in the 1980s, did that stop great films from being made? Maybe for a bit but now 20+ years later we're back to bareback ATM films with no worries by the performers about diseases. This is just like consumers coming back after the recession and levering up again because daddy needs his 60 inch tv. People have short memories (and Money McBags' short memories are mostly of He Ping Ping) and are generally optimistic so good news spurs them to repeat behaviors that may not be optimal for them in the long run. In other macro news, the CPI was up only.1% and was flat excluding food and energy (or you know, the things you actually need). The lack of an increase in CPI bodes well for the Federal Reserves' plan to keep interest rates low for an "extended period" as inflation looks like it will be pushed out for another few quarters until investors can actually finish counting all of the cash the US government printed (you all remember Money McBags' "Too big to count" hypothesis). The one small turd in the punchbowl today was that mortgage applications fell for the second straight week as people seem content to live in their current abodes and the game of flipping houses has finally passed like a painful kidney stone, Mickey Roarke's comeback, or one piece bathing suits.


On top of the good macro news, Bernanke was getting his Fed on today in front of Congress by saying that he doesn't plan to change any policy decisions but the recovery may be moderate due to high and prolonged unemployment, low construction demand, the poor fiscal condition of state and local governments, and Rasheed Wallace. Bernanke was quoted as saying about borrowing that "The decline in large part reflects sluggish loan demand and the fact that many potential borrowers no longer qualify for credit, both results of a weak economy." Luckily, banks have shorter memories than investors and it is only a matter of months before FICO 560 people are once again getting $500k loans to buy houses in states they don't work at variable interest rates. But hey, until then, rally on!!!!!!!
In stock news, JP Morgan beat estimates, grew income by 55%, and raised their outlook for the year. So fuck you right in the ear recession, you hear that (though maybe you won't hear it with a dick in your ear)? JPM earned $.74 per share which was $.10 above analyst guesses and revenue was $28.2B, ~$2B above guesses of $26.5B. While JPM's retail bank and customer card businesses are still struggling a bit, the investment bank blew it out thanks to strong fixed income trading. And if a weak retail business and strong fixed income trading don't bode well for the economy, then Money McBags didn't learn anything over these past few years. Oh wait, trading profits and a fuckshit consumer are exactly what got us in to this situation, ugh. But I guess there is something to say about the classics. CEO Jamie Dimon did say that “We continued to see delinquencies stabilize, and in some cases improve, in our credit portfolios,” which is a good sign, but then he added "and if they don't stabilize, we'll just create some complex products to trade with other banks and further boost our illusory profits." While Chase card may have struggled, at least the bad loans have been siphoned off into a holding company to separate the risk and to hopefully make investors forget about what happened and just concentrate on Chase's growth portfolio which won't need to be put in to it's own holding tank, until it does. In other stock news INTC crushed their quarter with eps coming in at $.43 which was well above last year's $.11 eps and revenue was up $3B to $10B. They also announced strong revenue guidance, an improving gross margin, and they will be hiring 1k to 2k people which will be their first new hires in 5 years, so take that unemployment rate. INTC's Q was so good that Money McBags may have to take it in to the bathroom and have a little time for himself with it while thinking about INTC's motherboards which are so sexy they can be considered MBILFs. Finally Apple announced that they are going to delay the iPad launch outside of the US because demand in the US has been stronger than the demand for accutane in Jessica Simpson's house or the female condom in Britney Spears' house.


In small cap news, AAPL's strong demand for the iPad could bode well for CRUS if CRUS actually has a chip in the iPad like they do the iPhone. The stock is reacting well today to the INTC blow out quarter and potentially the iPad news. Money McBags thinks they can earn $.73 next year but assumes only 12% topline growth so if their energy business can continue to come back and if their audio business just slows down a little from their current 80% growth rate, that number should be surpassed easier than a 3rd grader surpasses Kim Kardashian's reading level. The stock is now near $10, and remember Money McBags has been talking about CRUS since 1/12/10 when it was trading just under $8 and he mentioned he bought some on 1/29/10 when it had fallen below $7, so a >40% gain in 2+ months isn't too bad. Money McBags hopes you all joined him on this ride and have been able to take your lady friends (or man friends) out to many lobster tail and bj dinners. That said, they have $2 in cash so they are really trading at ~10x Money McBags admittedly cautious estimate for this year which is pretty fucking cheap for a company that sells a chip to the biggest fucking electronics seller/fad in the Universe. Also, JOEZ is rallying today after the huge sell off from their earnings. Money McBags is still on the sidelines here for reasons he has laid out over the past few days. Basically, if you're in the market today you can't lose, like flipping a two headed coin, having your brother be the Governor of the state you need to win in a contested election, or being Alexis Texas in a great ass contest. One stock that is down which Money McBags is going to start looking in to again is CKSW which produces the best logistics/scheduling software for fleets. The company announced a 15MM share shelf offering today which is really fucking odd since they only have 30MM shares outstanding so this would be hella dilutive if they actually went through with the full offering. Money McBags is going to look more in to this over the next few days as the company apparently has the best software, but a shelf like that is more perplexing than Jennifer Love Hewitt's career or an Amish computer camp.


Thursday, March 25, 2010
3/25/10 Midafternoon Report: Bailouts, stimulus, and earnings. Oh My!
The rally is on again as Germany says they will back Greece, earnings are crushing estimates, and Bernanke is going to continue to stimulate the economy like he's the delightful young actress Jessica Pare (moderately safe for work) and the economy is Money McBags. Bernanke spoke to the House Financial Services Committee today and he tried his best to use small words so the elected officials could understand him. Bernanke reiterated that "The economy continues to require the support of accommodative monetary policies" and cited the high unemployment numbers, the weak housing market, and the decline of Paul Reubens' career. He did say that the Fed has a plan to tighten monetary policy and he will do so at the appropriate time even if it causes Alan Greenspan to roll over in his grave. More importantly, new claims for unemployment fell by 14k to 442k which was 8k below economists' forecasts (forecasts called for it to be overcast with a chance for showers and instead it was sunny and thus caused the showers to be golden to the delight of urolagniacs everywhere). 11.1MM people are still claming unemployment which is only slightly fewer than the number of people in Ohio or the number of pornstars claiming to have seen Tiger's wood, so it is still a big fucking number. Economists think that if the new claims for unmeployment can drop to 425k, that could signal job growth, of course most of these same economists also thought that home prices could go up forever, that steady state unemployment could be achieved, and that Adam Smith actually had an invisible hand, so be careful to whom you listen (and as an aside, if Money McBags had an invisible hand it would be firmly attached to Bar Refaeli at all times).
In international news, Germany's Chancelor Angela Merkel told the EU and Greece that Germany would support aid to Greece if the IMF were to be involved and if the Greeks finally cleaned up the Parthenon (I mean seriously, it's been around for 2,500 years. Can someone in Greece do like 1 days work and just dust around the edges a bit?). France is backing the German plan which marks the first time these two countries have worked together since their ill-fated Broadway run in the musical Les Miserables Time We Had On Das Boot: A Love Story. Not only did Greece get positive news, but Dubai is putting up to $9.5B in to Dubai World and it's failing real estate business to make sure that the illusion of grandeur can continue. Dubai World creditors will be paid back in 5 to 8 years or just in time for the next bubble.
The big news of the day has been in the US stock markets where earnings have continued to impress like Beethoven on "Take your kid to work day" or Salma Hayek at a treasure chest convention. Best Buy easily beat their numbers posting a profit of $1.82 per share vs. analyst guesses of $1.79. They also gave full year guidance of $3.45 to $3.60 per share which is well above the $3.36 consensus analyst guess. Same store sales rose by 7% after the company cut prices on flat panel TVs and started offering free taint massages for any purchases over $2,500. Best Buy also announced further international expansion, continued stock buybacks, and Olivia Munn to be in charge of the Geek Squad's free "modem adujstment" promotion. In other stock news Qualcomm is off to the races after they raised their expectations for the second time. They now think Q2 earnings will be between $.56 and $.58 per share which is higher than analyst guesses of $.53 and higher than previous guidance of $.49 to $.53. They cited better licensing revenues and the addition of crack cocaine directly into their Snapdragon chipset. Both QCOM and BBY are up 7%+ on the day as investors run to chase good news like Alabamans chase leprechauns.
In small cap news, Money McBags ditched his RICK shares and it really hurt him to do so. The easy money had been made, though in positive news for those still holding RICK, Money McBags will be putting a portion of his >50% profits back in to Rick's business through the purchase of many Jack and Cokes without the Coke while watching the fine classically trained dancers. In other small cap news, you might be able to make a momentum trade on CRTX. Money McBags wrote about CRTX after their Q in the first week of March and they seem to have picked up some steam since then. They are up 7% today on no news and slightly higher than average volume, but they have been steadily rising for the past couple of weeks. The company still has a ton of risk as their top selling drugs are in decline, they gave away controlling interest of the company to Italian pharma company Chiesi last year in order to help their balance sheet and acquire new drugs, and their operating record is thinner than Keira Knightley. If you believe their projections though, they are trading at only ~1.5x sales and that is way too low for a real company to be valued (of course this may not be a real company like, Nohjay Nimpson may not be a real name, oh wait, scratch that). So if you're feeling lucky, this is a total momentum trade with absolutely no news behind it other than valuation seems relatively cheap and thus your downside should be limited (that is if the company's proections are accurate).


In international news, Germany's Chancelor Angela Merkel told the EU and Greece that Germany would support aid to Greece if the IMF were to be involved and if the Greeks finally cleaned up the Parthenon (I mean seriously, it's been around for 2,500 years. Can someone in Greece do like 1 days work and just dust around the edges a bit?). France is backing the German plan which marks the first time these two countries have worked together since their ill-fated Broadway run in the musical Les Miserables Time We Had On Das Boot: A Love Story. Not only did Greece get positive news, but Dubai is putting up to $9.5B in to Dubai World and it's failing real estate business to make sure that the illusion of grandeur can continue. Dubai World creditors will be paid back in 5 to 8 years or just in time for the next bubble.

The big news of the day has been in the US stock markets where earnings have continued to impress like Beethoven on "Take your kid to work day" or Salma Hayek at a treasure chest convention. Best Buy easily beat their numbers posting a profit of $1.82 per share vs. analyst guesses of $1.79. They also gave full year guidance of $3.45 to $3.60 per share which is well above the $3.36 consensus analyst guess. Same store sales rose by 7% after the company cut prices on flat panel TVs and started offering free taint massages for any purchases over $2,500. Best Buy also announced further international expansion, continued stock buybacks, and Olivia Munn to be in charge of the Geek Squad's free "modem adujstment" promotion. In other stock news Qualcomm is off to the races after they raised their expectations for the second time. They now think Q2 earnings will be between $.56 and $.58 per share which is higher than analyst guesses of $.53 and higher than previous guidance of $.49 to $.53. They cited better licensing revenues and the addition of crack cocaine directly into their Snapdragon chipset. Both QCOM and BBY are up 7%+ on the day as investors run to chase good news like Alabamans chase leprechauns.


In small cap news, Money McBags ditched his RICK shares and it really hurt him to do so. The easy money had been made, though in positive news for those still holding RICK, Money McBags will be putting a portion of his >50% profits back in to Rick's business through the purchase of many Jack and Cokes without the Coke while watching the fine classically trained dancers. In other small cap news, you might be able to make a momentum trade on CRTX. Money McBags wrote about CRTX after their Q in the first week of March and they seem to have picked up some steam since then. They are up 7% today on no news and slightly higher than average volume, but they have been steadily rising for the past couple of weeks. The company still has a ton of risk as their top selling drugs are in decline, they gave away controlling interest of the company to Italian pharma company Chiesi last year in order to help their balance sheet and acquire new drugs, and their operating record is thinner than Keira Knightley. If you believe their projections though, they are trading at only ~1.5x sales and that is way too low for a real company to be valued (of course this may not be a real company like, Nohjay Nimpson may not be a real name, oh wait, scratch that). So if you're feeling lucky, this is a total momentum trade with absolutely no news behind it other than valuation seems relatively cheap and thus your downside should be limited (that is if the company's proections are accurate).

Tuesday, March 2, 2010
3/2/10 Midevening Report: Market rises as member of the Fed retires, economists worried more retirements could cause bubble
The Fed is getting all jiggy with the markets today and the markets seem to like it. First Ben Bernanke's number one henchman, the honorable Donald L. Kohn who in 40 years of service at the Fed never saw a market he couldn't inflate, announced he is resigning from his position as Vice Chairman of the Fed in order to pursue other ventures more productive to society like finding out where the all the bees went, calculating Pi to the 1 billionth decimal (hint: 7), or figuring out how to get a money shot in lesbian porn (and squirting is not an acceptable answer). When asked why he was retiring, Kohn cited his age, his family, and his annoyance at always having to leave the seat down for Janet Yellen in the Federal Reserve bathroom (and I am told the right stall still contains the graffiti from 1934 of former Fed Chairman Eugene Black stating "Once you go Black, rates will never come back," which helps explain why he was only in that position for only 1 year). Journalists have begun speculating on who Obama will nominate to fill Kohn's seat at the Fed with leading candidates being the esteemed former President of Harvard Larry Summers who was forced to resign from that position due to a vote of "no confidence" (and seeing how the Fed is supposed to help instill confidence in to the economy, Summer's "no confidence" vote may be a bit of a red flag), some lady named Christina Romer who actually looks a bit like Larry Summers in drag (no really, check it out, this is Larry Summers, this is Christina Romer, have you ever seen them in the same room?), and of course When Genius Prevailed's own Money McBags (and Money McBags will certainly turn down the nomination as it would impede on his time at his not safe for working at the Fed, yet imminently important, hobby of guessing muffs (NSFW)). Not only is Donald Kohn retiring, but rogue Federal Reserve Board Member Thomas "T-Ho" Hoenig who is the yin to Bernanke's yang, the Mary Kate to Bernanke's Ashley, and the turd to Bernanke's punchbowl, is out again saying rates need to move up sooner rather than later. While Benny B seemingly dissed T-Ho last week when congress axed him about rates and he said they would be kept low for an extended period of time, T-Ho got all upitty on Benny B and went on CNBC to air his grievances about indefinite low rates, inflation, and Benny B not keeping it real (rates that is). T-Ho said: "You are inviting future problems" and then removed his gold teef, took a swig on his 40 of Mickeys, and reiterated that a zero percent fed-funds rate is "inviting future excesses, and we all know my baby momma ain't need no more excesses." But he didn't stop there, T-Ho took it one step further, opining "I think we shouldn't be guaranteeing markets a zero rate for an extended period." Rates "could be higher, and the effects would be minor" and "We should start that process sooner rather than later." He then lamented that that "Bitch ass Benny B better recognize and check himself before he wrecks himself, because this aint no round the way girl he's messing with, this is Uncle fucking Sam."
In international news, continued hopes of a Greek bailout and a rally in India hepled the US market today. Greece was expected to release their austerity plan which was to shave $3.5B off of their deficit and was to include an increase in their value-added sales tax on things such as Ouzo, saganaki, and greek sodas. India's government reported increases in manufacturing and exports, which along with strong sales from leading auto producer TaTa Motors (who are now said to beoffering lube jobs with their TaTas), helped send the market to it's high for the month.
In US stock news, Ford became the top auto seller for the month with a 43% increase in sales thanks to the Toyota recall and consumers apparently not giving a shit about buying crappy cars. This was the first time in 12 years Ford has outsold GM in a month which means they are 3 years ahead of their 15 year plan. In earnings, Staples Q4 profit dropped 18% as a result of restructuring and disappointing sales of big ticket items like furniture and oversized checks for lottery winners. The stock dropped 10% as their guidance of $1.23 to $1.33 per share was worse than Rosie O'Donnell's girlfriend's breath after downing a lipsmacking day old tuna fish sandwich. Estimates were for $1.40 per share and anytime a company lowers earnings by greater than 10%, nothing good happens. Also, QCOM was up 7% after taking shareholder friendly actions of raising their dividend, announcing a big share buyback, and booking Hannah Hilton as the lunchtime entertainment for their next shareholder meeting (and Money McBags wishes she would hold his shares).
In small cap news a flurry of companies reported today with QCOR shaking off their string of bad quarters while NTRI and NLS helped their shareholders lose weight by making them hurl after each company put up craptastic quarters. Money McBags will dive into NTRI and NLS a bit later in the week, though he welcomes NLS supporter and long time When Genius Prevailed reader Matty McSacks to chime in and help Money McBags understand which of the 4 earnings from continuing operations numbers realeased today is best to use to evaluate NLS's business. Money McBags hasn't seen a release so confusing since he hit puberty and shot his first load to the imagined Lisa Whelchel-Nancy McKeon tryst which would have redefined Edna's Edibles. As for QCOR, Money McBags broke them down in December concluding that "they could have real upside if they continue to penetrate the MS market and can get on-label IS approval." Money McBags was waiting to see some more results though before buying as they had run in to reimbursement issues and some sales hiccups and today they certainly put up some strong results with 223% growth in their MS segment and 56% growth in their paid commercial IS segment, plus they had some sales into the nephrotic syndrome market. Money McBags will break QCOR down later in the week as well as he is pressed for time today but today's 18% rise was likely a short squeeze (and Money McBags realizes he said that about the last time QCOR rallied, but there is something to say about consistency), that said, if they are now back up to a $.52 annual eps run rate with their $.13 eps quarter today, there is no reason they shouldn't trade at 15x that and thus put their value at around $7.50 per share. The company has been well run and is shareholder friendly, but they need to continue to execute.


In international news, continued hopes of a Greek bailout and a rally in India hepled the US market today. Greece was expected to release their austerity plan which was to shave $3.5B off of their deficit and was to include an increase in their value-added sales tax on things such as Ouzo, saganaki, and greek sodas. India's government reported increases in manufacturing and exports, which along with strong sales from leading auto producer TaTa Motors (who are now said to beoffering lube jobs with their TaTas), helped send the market to it's high for the month.

In US stock news, Ford became the top auto seller for the month with a 43% increase in sales thanks to the Toyota recall and consumers apparently not giving a shit about buying crappy cars. This was the first time in 12 years Ford has outsold GM in a month which means they are 3 years ahead of their 15 year plan. In earnings, Staples Q4 profit dropped 18% as a result of restructuring and disappointing sales of big ticket items like furniture and oversized checks for lottery winners. The stock dropped 10% as their guidance of $1.23 to $1.33 per share was worse than Rosie O'Donnell's girlfriend's breath after downing a lipsmacking day old tuna fish sandwich. Estimates were for $1.40 per share and anytime a company lowers earnings by greater than 10%, nothing good happens. Also, QCOM was up 7% after taking shareholder friendly actions of raising their dividend, announcing a big share buyback, and booking Hannah Hilton as the lunchtime entertainment for their next shareholder meeting (and Money McBags wishes she would hold his shares).
In small cap news a flurry of companies reported today with QCOR shaking off their string of bad quarters while NTRI and NLS helped their shareholders lose weight by making them hurl after each company put up craptastic quarters. Money McBags will dive into NTRI and NLS a bit later in the week, though he welcomes NLS supporter and long time When Genius Prevailed reader Matty McSacks to chime in and help Money McBags understand which of the 4 earnings from continuing operations numbers realeased today is best to use to evaluate NLS's business. Money McBags hasn't seen a release so confusing since he hit puberty and shot his first load to the imagined Lisa Whelchel-Nancy McKeon tryst which would have redefined Edna's Edibles. As for QCOR, Money McBags broke them down in December concluding that "they could have real upside if they continue to penetrate the MS market and can get on-label IS approval." Money McBags was waiting to see some more results though before buying as they had run in to reimbursement issues and some sales hiccups and today they certainly put up some strong results with 223% growth in their MS segment and 56% growth in their paid commercial IS segment, plus they had some sales into the nephrotic syndrome market. Money McBags will break QCOR down later in the week as well as he is pressed for time today but today's 18% rise was likely a short squeeze (and Money McBags realizes he said that about the last time QCOR rallied, but there is something to say about consistency), that said, if they are now back up to a $.52 annual eps run rate with their $.13 eps quarter today, there is no reason they shouldn't trade at 15x that and thus put their value at around $7.50 per share. The company has been well run and is shareholder friendly, but they need to continue to execute.


Wednesday, February 24, 2010
2/24/10 Midafternoon Report: Bernanke channels his inner Greenspan and promises to keep rates low until the next bubble
Dizzam, Benny B went in front of the House Financial Services Commitee today and let everyone know that rates will be kept low for a more "extended period" than a menometrorrhagia sufferer. Despite last week's back and forth between Bernanke and his henchman Thomas "T-Ho" Hoenig about the language used by the Fed in their minutes (and Money McBags would vote for Esperanto just to switch things up), Benny B held to his guns and let congress know he isn't going to raise rates until he sees the whites of the recovery's eyes (or the P in their GDP). Bernanke also said he believes the recent uptick in business growth was just an inventory restocking which is exactly what Money McBags has been yelling through the gold-plated window of his ivory tower for the past several months.
Bernanke stated: “As the impetus provided by the inventory cycle is temporary, and as the fiscal support for economic growth likely will diminish later this year, a sustained recovery will depend on continued growth in private-sector final demand for goods and services." (Bolding is from Money McBags, multisyllabic, excessive, and painfully boring verbiage is from Bernanke as apparently he gets paid by the snore).
Bernanke cited the diminishing skills of workers who have been forced into long term unemployment, the current deficit, and Hannah Hilton's apparent cinematic retirement as concerns potentially inhibiting a full recovery. He did say he expected the unemployment rate to drop to 7% by 2012, but he didn't say that it was likely going to be as a result of a massive numerator shift caused by those currently longterm unemployed workers starving to death in the new Dust Bowl, or aptly named for our times, The Capital One Mortgage Bowl: What Used to Be in Your Wallet? Bernanke also said that inflation would be "subdued" for some time as the US printed so much money that investors are still trying to count it to figure out exactly how much there is, so until that time, the market will remain blissfully ignorant. Call it the "Too Big To Count" theory.
In other macro news, prices of new homes fell surprising everyone except for the 15MM to 20MM unemployed Americans. Despite the government extending the tax credit for first time home buyers, purchases still declined by 11% and fell to their all-time low as any first time home buyers had likely already taken advantage of the tax credit last year by rushing in to buy before the previous deadline. Therefore extending the tax credit was like offering lunch to the Nathan's Hot Dog Eating Contest contestants immediately after the final gag sounded. There is currently a 9 month inventory of houses on the market and 3MM more houses are forecast to be foreclosed upon this year which is great for vermin, but not so great for the economy.
In stock news, Dollar Tree destroyed their analyst estimates as if those estimates were Joanie's rectum and they were Chachi after a blue-balled night of doing body shots off of Pinky Tuscadero. DLTR beat estimates of $1.44 eps by $.08 thanks to better gross margins and gave guidance well above analyst estimates for Q1 and the full year with EPS slated to be $3.96 to $4.23 for 2010. They also generate a ton of cash and for those who have been on the planet Melmac for the past few years living off of toasted feline (and to be honest, if it were Jayde Nicole's "cat" being served on Melmac, Money McBags would immediately build a spaceship) and aren't familiar with the company, they sell incredibly cheap shit in a recessionary environment. They are now trading at around 14x 2010 guidance but this environment for them should be as profitable as the guy operating the lifeboat booth on the Titanic or whoever was selling bullets at the Alamo. Money McBags has not followed DLTR as closely as he should have, but the story makes sense and the valuation isn't horrible. They'll probably trade down tomorrow after today's jump, but this stock is worth investigating further.
As for small caps, CTGX reported their quarter last night and it was inline but their guidance was better than Money McBags was expecting. Money McBags previewed ther quarter the other day and was perfectly content with their release last night as he was just expecting more of the same for now in their core business and that is what he got. Their revenue for the Q was down 19% with equal declines in their solutions and staffing business. Honestly, Money McBags can't do anything but yawn about this as it is completly irrelevant to the story as he previously outlined. As long as the core business doesn't blow up (and there is really no reason it should), the EMR business CTGX is in should provide the real growth for this company over the next 3 to 5 years. This was Money McBags favorite quote from their press release (he'd quote their call, but it was fantastically bland, like a primetime sitcom or anything written by that Michael Crichton guy):
"Looking further out, with the billions of dollars in federal stimulus money for EMRs from ARRA, Medicare, and Medicaid still unspent, we expect demand for EMR implementation support will steadily accelerate as these funds become available and access to the credit markets opens up for providers. Based on our deep EMR experience for large providers and communitywide health information exchanges, we are confident in our ability to secure significant new EMR work over the next three years, particularly as the 2014 deadline for having systems meeting meaningful use criteria in place draws closer." (Bolding again from Money McBags).
That is pretty much all you need to know. Now guidance for 2010 is for eps of $.46-$.56 on 11% revenue growth. So they are trading at around 15.5x the midpoint of guidance and they actually see their staffing business picking up into the year and have begun hiring. Also, their balance sheet is cleaner than the grout on germaphobe's tiled bathroom floor and they are buying back shares. There is not much reason for the company to take off right now, but EMR is coming so this stock is the definition of buy and hold, especially as it isn't horribly priced (it isn't all that cheap though).
Bernanke stated: “As the impetus provided by the inventory cycle is temporary, and as the fiscal support for economic growth likely will diminish later this year, a sustained recovery will depend on continued growth in private-sector final demand for goods and services." (Bolding is from Money McBags, multisyllabic, excessive, and painfully boring verbiage is from Bernanke as apparently he gets paid by the snore).
Bernanke cited the diminishing skills of workers who have been forced into long term unemployment, the current deficit, and Hannah Hilton's apparent cinematic retirement as concerns potentially inhibiting a full recovery. He did say he expected the unemployment rate to drop to 7% by 2012, but he didn't say that it was likely going to be as a result of a massive numerator shift caused by those currently longterm unemployed workers starving to death in the new Dust Bowl, or aptly named for our times, The Capital One Mortgage Bowl: What Used to Be in Your Wallet? Bernanke also said that inflation would be "subdued" for some time as the US printed so much money that investors are still trying to count it to figure out exactly how much there is, so until that time, the market will remain blissfully ignorant. Call it the "Too Big To Count" theory.


In other macro news, prices of new homes fell surprising everyone except for the 15MM to 20MM unemployed Americans. Despite the government extending the tax credit for first time home buyers, purchases still declined by 11% and fell to their all-time low as any first time home buyers had likely already taken advantage of the tax credit last year by rushing in to buy before the previous deadline. Therefore extending the tax credit was like offering lunch to the Nathan's Hot Dog Eating Contest contestants immediately after the final gag sounded. There is currently a 9 month inventory of houses on the market and 3MM more houses are forecast to be foreclosed upon this year which is great for vermin, but not so great for the economy.
In stock news, Dollar Tree destroyed their analyst estimates as if those estimates were Joanie's rectum and they were Chachi after a blue-balled night of doing body shots off of Pinky Tuscadero. DLTR beat estimates of $1.44 eps by $.08 thanks to better gross margins and gave guidance well above analyst estimates for Q1 and the full year with EPS slated to be $3.96 to $4.23 for 2010. They also generate a ton of cash and for those who have been on the planet Melmac for the past few years living off of toasted feline (and to be honest, if it were Jayde Nicole's "cat" being served on Melmac, Money McBags would immediately build a spaceship) and aren't familiar with the company, they sell incredibly cheap shit in a recessionary environment. They are now trading at around 14x 2010 guidance but this environment for them should be as profitable as the guy operating the lifeboat booth on the Titanic or whoever was selling bullets at the Alamo. Money McBags has not followed DLTR as closely as he should have, but the story makes sense and the valuation isn't horrible. They'll probably trade down tomorrow after today's jump, but this stock is worth investigating further.

As for small caps, CTGX reported their quarter last night and it was inline but their guidance was better than Money McBags was expecting. Money McBags previewed ther quarter the other day and was perfectly content with their release last night as he was just expecting more of the same for now in their core business and that is what he got. Their revenue for the Q was down 19% with equal declines in their solutions and staffing business. Honestly, Money McBags can't do anything but yawn about this as it is completly irrelevant to the story as he previously outlined. As long as the core business doesn't blow up (and there is really no reason it should), the EMR business CTGX is in should provide the real growth for this company over the next 3 to 5 years. This was Money McBags favorite quote from their press release (he'd quote their call, but it was fantastically bland, like a primetime sitcom or anything written by that Michael Crichton guy):
"Looking further out, with the billions of dollars in federal stimulus money for EMRs from ARRA, Medicare, and Medicaid still unspent, we expect demand for EMR implementation support will steadily accelerate as these funds become available and access to the credit markets opens up for providers. Based on our deep EMR experience for large providers and communitywide health information exchanges, we are confident in our ability to secure significant new EMR work over the next three years, particularly as the 2014 deadline for having systems meeting meaningful use criteria in place draws closer." (Bolding again from Money McBags).
That is pretty much all you need to know. Now guidance for 2010 is for eps of $.46-$.56 on 11% revenue growth. So they are trading at around 15.5x the midpoint of guidance and they actually see their staffing business picking up into the year and have begun hiring. Also, their balance sheet is cleaner than the grout on germaphobe's tiled bathroom floor and they are buying back shares. There is not much reason for the company to take off right now, but EMR is coming so this stock is the definition of buy and hold, especially as it isn't horribly priced (it isn't all that cheap though).
Friday, February 19, 2010
2/19/10 Midafternoon Report: Core inflation tame, good news for those who don't eat or use energy
The market hung in there today despite Ben Bernanke's surprising discount rate raise after the market closed yesterday. Bernanke continues to think outside of the box in managing the economy (and as long as it isn't Hannah Hilton's box, then Money McBags is fully on board because one should only think inside her box, never outside of it). There is no telling what Bernanke will do next as a Federal Reserve Chairman hasn't done anything as radical as he has since Marriner S. Eccles wore black shoes with a brown belt on day back in 1937. Money McBags is all in favor of the proactivity of the Fed and anxiously awaits their next move, whether it be reducing their balance sheet, paying interest on bank loans, or having the head of the Cleveland branch of the Fed, Sandra Pianalto, man the kissing booth at the Fed's next holiday party (what, you'd prefer Janet Yellen?).
The Dollar is now at its nine month high against the Euro, reaching $1.35 to the Euro, thanks to the Fed actions which means that all of the unemployed people who couldn't afford to book vacations to see the leaning tower of Pisa this winter can now hypothetically be able to at least afford to check a bag. CPI data also came out today and showed inflation to be less than expected except for a couple of small things called energy and food. Excluding food and fuel costs, prices fell .1% which was the first decline in over 25 years. So as long as you don't eat or go anywhere in the fucking car which you probably have to sell anyway to make the mortgage payments on the house you couldn't afford but were able to get a loan for so the endowment fund at the University of My Left Nut (go fighting Ballhawks!) could get a little extra yield on their fixed income portfolio by having bankers slice up pools of those mortgages which enabled those same bankers to buy even more coke and purchase hookers with fewer diseases, everything should be ok. For fucksake, we're not hunter-gatherers anymore (though if we were, I would hunt and gather me some Amanda Seyfried) and thus excluding food and fuel costs from the CPI is like excluding money shots from bukakke films or excluding General Winfield Scott from a list of greatest guys with the first name Winfield (and a big shout out to Old Fuss and Feathers, all the Whigs in the house give me a "hell yeah!").
In stock news today, DELL apparently has been spending way too much time trying to find the Erin Andrews peephole video and apparently downloaded a virus in the process as they are down 6% on last night's disappointing quarter. Revenue grew 11% while profit dropped 4.8%. We have a word for that on When Genius Prevailed, it's called "bad fucking business" (and yes Money McBags knows that is actually three words but like DELL, he is giving you 200% more for the same price). Dell's continued reliance on discounting is good for consumers (assuming they wanted a shitty Dell computer with customer service so bad that it that makes Britney Spears teaching you bernouilli distributions seem helpful), but not good for shareholders. Granted all PCs not starting with an "i" are essentially commodities so price competition is inherrent to the market, but negative operating leverage for a business is like a female with a hairy ass, it's uninteresting, unbecoming, and frankly unnatural. In other large cap news FSLR reported a decent quarter, beating analyst estimates but then guided to increased margin pressure in the second half of the year as apparently their main source of energy, the sun, is free. Solar stocks are being eclipsed by the market today as a result.
In small cap news, JOEZ continues to rally (and Money McBags broke down JOEZ quarter a couple of weeks ago) while for some reason HIL continues to crumble like poorly installed dry wall (and that is punny because HIL oversees commercial construction). Money McBags has been a fan of HIL as they are diversified globally, have had solid performance, and don't take on any building risk. They are hired to litigate and to manage the building process. The company is now trading at 10x estimates, around 1.5x book value, and close to 8.5x EV/EBITDA. They have been acquiring companies in geographies they are not in and think their claims business should start coming back. The stock is down by close to 1/3 in he past four months and now it seems to be fairly cheap. Money McBags is unsure why it has been hit so badly as it offers a nice way to diversify into real estate without taking the building balance sheet risk. So your homework for the weekend, other than taking out the trash, is to figure out what is going on with HIL. Money McBags will dig into it a bit more next week and see if he can't find a reason for the four month sell off because if there is nothing nefarious going on (like a Goldman Sachs Greek bond placement and currency swap or a Heidi Montag record promotion) then this could be a good entry point.
So enjoy the weekend and Money McBags will be back on Monday.
The Dollar is now at its nine month high against the Euro, reaching $1.35 to the Euro, thanks to the Fed actions which means that all of the unemployed people who couldn't afford to book vacations to see the leaning tower of Pisa this winter can now hypothetically be able to at least afford to check a bag. CPI data also came out today and showed inflation to be less than expected except for a couple of small things called energy and food. Excluding food and fuel costs, prices fell .1% which was the first decline in over 25 years. So as long as you don't eat or go anywhere in the fucking car which you probably have to sell anyway to make the mortgage payments on the house you couldn't afford but were able to get a loan for so the endowment fund at the University of My Left Nut (go fighting Ballhawks!) could get a little extra yield on their fixed income portfolio by having bankers slice up pools of those mortgages which enabled those same bankers to buy even more coke and purchase hookers with fewer diseases, everything should be ok. For fucksake, we're not hunter-gatherers anymore (though if we were, I would hunt and gather me some Amanda Seyfried) and thus excluding food and fuel costs from the CPI is like excluding money shots from bukakke films or excluding General Winfield Scott from a list of greatest guys with the first name Winfield (and a big shout out to Old Fuss and Feathers, all the Whigs in the house give me a "hell yeah!").
In stock news today, DELL apparently has been spending way too much time trying to find the Erin Andrews peephole video and apparently downloaded a virus in the process as they are down 6% on last night's disappointing quarter. Revenue grew 11% while profit dropped 4.8%. We have a word for that on When Genius Prevailed, it's called "bad fucking business" (and yes Money McBags knows that is actually three words but like DELL, he is giving you 200% more for the same price). Dell's continued reliance on discounting is good for consumers (assuming they wanted a shitty Dell computer with customer service so bad that it that makes Britney Spears teaching you bernouilli distributions seem helpful), but not good for shareholders. Granted all PCs not starting with an "i" are essentially commodities so price competition is inherrent to the market, but negative operating leverage for a business is like a female with a hairy ass, it's uninteresting, unbecoming, and frankly unnatural. In other large cap news FSLR reported a decent quarter, beating analyst estimates but then guided to increased margin pressure in the second half of the year as apparently their main source of energy, the sun, is free. Solar stocks are being eclipsed by the market today as a result.
In small cap news, JOEZ continues to rally (and Money McBags broke down JOEZ quarter a couple of weeks ago) while for some reason HIL continues to crumble like poorly installed dry wall (and that is punny because HIL oversees commercial construction). Money McBags has been a fan of HIL as they are diversified globally, have had solid performance, and don't take on any building risk. They are hired to litigate and to manage the building process. The company is now trading at 10x estimates, around 1.5x book value, and close to 8.5x EV/EBITDA. They have been acquiring companies in geographies they are not in and think their claims business should start coming back. The stock is down by close to 1/3 in he past four months and now it seems to be fairly cheap. Money McBags is unsure why it has been hit so badly as it offers a nice way to diversify into real estate without taking the building balance sheet risk. So your homework for the weekend, other than taking out the trash, is to figure out what is going on with HIL. Money McBags will dig into it a bit more next week and see if he can't find a reason for the four month sell off because if there is nothing nefarious going on (like a Goldman Sachs Greek bond placement and currency swap or a Heidi Montag record promotion) then this could be a good entry point.


So enjoy the weekend and Money McBags will be back on Monday.
Thursday, February 18, 2010
2/18/10 Midevening Report : Bernanke preemptively raises discount rate, causes Alan Greenspan to roll over in his grave
Aw shit, it is now on like donkey kong as the Fed is getting serious about some shit. This ain't your Greenspan pushover, lolligagging, lobster tails and blow jobs for everyone, bubble creating Federal Reserve. No siree, this Bernanke guy is a straight up pimp and will bitch slap the market back to reality and remind them not to take daddy's money before they get too uppity on him. With the markets running off of a 3 day orgy filled with earnings, mediocre economic news, and a potential bailout to get the EU out of the greek headlock in which they have been painfully trapped, Bernanke had had enough. We all remember when the fed minutes were released yesterday and one of Bernanke's henchman, T-Ho (Fed Reserve of KC bank president Thomas Hoenig) started to warn Ben about getting high off his own supply by keeping rates too low. Well Benny B took that to heart and after the market closed he took out his pimp hand and smacked the shit out of the market by surprisingly raising the discount rate to 75bps while yelling "That's right market, don't forget, I'm you're daddy. Come on, say it. Who's your daddy? Let me hear it. You know you want it tight in the discount window." This is the first time the rate has been increased in three years and will likely halt the market's rally tomorrow.
Aside from Bernanke trying to win his cock-off with the market, macro news was mixed today with the Philly Fed saying manufacturing had picked up again and new orders are at their highest levels in 5 years (of course in Philly, those new orders are for Uzis, Butterscotch Krimpets, and fecal matter to make the city even shittier than it is). New claims for unemployment also came out today and were worse than expectations, rising by 31k to 473k as opposed to falling as analysts had expected. Money McBags has been through this before, but if you're an analyst, can you at least get the direction correct? For fucksake you have a 50% chance, I mean it's not like the 33% chance you have in guessing "man, woman, or tranny?" with Kathleen Turner. Finally the PPI came out today (as opposed to the pee pee eye that landed R Kelly on trial) and was up 1.4% signalling inflation. While the core rate was only up .3%, it was still worse than the .1% expectation. The point is, inflation is coming and it's a good thing Bernanke looks to be proactive about it.
WMT had their earnings announcement today and beat earnings expectations yet had negative same store sales growth as a result of declining traffic. Their guidance for Q1 was also almost as bleak as John Tyler's 1844 re-election campaign or Heidi Montag's Celebrity Jeopardy! prospects as they said it will be a challenging quarter. The stock was down moderately today but if Bernanke is determined to quiet the market, shares of WMT may become more interesting if they fall another 5%.
Finally in small cap news WILC was down 10%. Really? No, really? There are people who want to puke out a company trading at less than 4x EV/EBITDA, less than 10x earnings (or 5x earnings if you take out the 50% cash they have on the balance sheet), with growth prospects to potentially double revenues? Seriously? Unless you think CEO Gee Willi Zwi Williger is blowing smoke out of his shofar and is fooling his auditors and submitting his financials in crayon on the back of a discarded yarmulke, there is absoltuely no fucking reason to be selling this stock here. It is still cheaper than a pail of salt water on the sunken island of Atlantis or the self respect of an 18 year old wanna be model on her first Hollywood casting couch. Yeah, Money McBags knows it is a weird fucking company (he broke it all down for you way back in 2009) and he also knows that the volume on this stock tends to be thinner than a bulimic with an oversensitive gag reflex, but for fucksake, what is it going to trade down to? Cash? A business earning money with no debt and growing is going to trade down to cash (which is only 50% downside from here)? If that's the case than Money McBags clearly has no idea what he is doing and needs to get of this business and into whatever idiots do, like maybe politics, making oven mitts, or running the LA Clippers. Unless this company is completely full of shit like a constipated political consultant, it is a fucking screaming buy. And yes Money McBags owns it, so yes he is talking up his book. Full fucking disclosure, as always.
Aside from Bernanke trying to win his cock-off with the market, macro news was mixed today with the Philly Fed saying manufacturing had picked up again and new orders are at their highest levels in 5 years (of course in Philly, those new orders are for Uzis, Butterscotch Krimpets, and fecal matter to make the city even shittier than it is). New claims for unemployment also came out today and were worse than expectations, rising by 31k to 473k as opposed to falling as analysts had expected. Money McBags has been through this before, but if you're an analyst, can you at least get the direction correct? For fucksake you have a 50% chance, I mean it's not like the 33% chance you have in guessing "man, woman, or tranny?" with Kathleen Turner. Finally the PPI came out today (as opposed to the pee pee eye that landed R Kelly on trial) and was up 1.4% signalling inflation. While the core rate was only up .3%, it was still worse than the .1% expectation. The point is, inflation is coming and it's a good thing Bernanke looks to be proactive about it.

WMT had their earnings announcement today and beat earnings expectations yet had negative same store sales growth as a result of declining traffic. Their guidance for Q1 was also almost as bleak as John Tyler's 1844 re-election campaign or Heidi Montag's Celebrity Jeopardy! prospects as they said it will be a challenging quarter. The stock was down moderately today but if Bernanke is determined to quiet the market, shares of WMT may become more interesting if they fall another 5%.
Finally in small cap news WILC was down 10%. Really? No, really? There are people who want to puke out a company trading at less than 4x EV/EBITDA, less than 10x earnings (or 5x earnings if you take out the 50% cash they have on the balance sheet), with growth prospects to potentially double revenues? Seriously? Unless you think CEO Gee Willi Zwi Williger is blowing smoke out of his shofar and is fooling his auditors and submitting his financials in crayon on the back of a discarded yarmulke, there is absoltuely no fucking reason to be selling this stock here. It is still cheaper than a pail of salt water on the sunken island of Atlantis or the self respect of an 18 year old wanna be model on her first Hollywood casting couch. Yeah, Money McBags knows it is a weird fucking company (he broke it all down for you way back in 2009) and he also knows that the volume on this stock tends to be thinner than a bulimic with an oversensitive gag reflex, but for fucksake, what is it going to trade down to? Cash? A business earning money with no debt and growing is going to trade down to cash (which is only 50% downside from here)? If that's the case than Money McBags clearly has no idea what he is doing and needs to get of this business and into whatever idiots do, like maybe politics, making oven mitts, or running the LA Clippers. Unless this company is completely full of shit like a constipated political consultant, it is a fucking screaming buy. And yes Money McBags owns it, so yes he is talking up his book. Full fucking disclosure, as always.
Wednesday, February 17, 2010
2/17/10 Midevening Report: Fed hints at reversing stimulus, starts by canceling Bernanke's Playboy subscription
The market was up today like a hooker's skirt in Tiger Wood's SUV. The rally was driven by earnings, earnings, earnings and some macro data. Apparently people are still building houses as housing starts hit their 6-month high, rising 2.8% to an annual rate of 591k. This marginally beat expectations and should be a good sign for the economy, even if half of the houses were built from legos and the other half have already been forelcosed on. In other macro news, the Fed announced that industrial output grew .9% which also beat expectations with capacity utilization coming in at 72%, 8% below the average from the last 37 years. So there is still room for the economy to rebound and thus produce more of those delightful "For Sale" signs to go in front yards, printers to print out resumes, and muzzles to put over Lady Gaga's face. Also, import prices rose by 1.4% signalling inflation may be on the way (and for those of you who need a less subtle signal: INFLATION IS COMING!! And Ben Bernanke is going to have to make inflation think long and hard about baseball for him to try to stop it from coming). Many analysts were unphased by the rise in import prices claiming oil and natural gas drove up prices, so I guess it's good we don't rely on those fuels at all or else we might have to worry a bit more about the dollar. Phew.
There was one piece of macro news which caused a brief sell-off before the market put back on its pearl necklace and returned to the ball (and yes, all of those were very bad puns). The minutes came out today from the last FOMC meeting and the head of the Kansas City branch of the Fed, Thomas Hoenig (known at the Fed as T-Ho), was the one dissenting vote on interest rates. T-Ho got all up in Benny B's grill and axed him why they needed to say the fed funds rate would remain low for an "extended period," preferring to change the language to say the fed funds rate would remain low for "some time, and shit." The minutes also revealed that the Fed is starting to look at downsizing their balance sheet and selling into the market the toxic assets, I mean mortgages, they previously bought. The key message here being that further stimulus to help the economy may be less likely than Brooklyn Decker dumping Andy Roddick for the first guy eliminated from next season's The Biggest Loser. The Fed might actually be doing something smart here by looking to get in front of a bubble and stopping it before it happens rather than pulling an Alan Greenspan and blowing hot air into it like it was Andrea Mitchell's rectum.
In earnings news, Deere's profit climbed 19% and they raised forecasts thanks to strength in "large ag equipment", or what's more commonly known as: "Rosie O'Donnell's dildos." Also, WFMI not only had a kashi-tastic quarter as Money McBags predicted yesterday, but is was double fiber kashi-tastic. WFMI same store sales were up 3.5% and they gave total revenue guidance for 10.5% growth in 2010 while raising full year earnings guidance to $1.20 to $1.25 per share, about 10% above current estimates. Yeah, it was a good Q but they are now trading at around 25x 2011 earnings which wouldn't be so bad if they were growing by more than 10%. Of course, EBITDA was up 25% and they raised EBITDA guidance by about 5% to $635MM-$685MM for 2010 which means they're trading at around 7x to 7.5x 2010 EV/EBITDA which actually isn't all that unreasonable. Money McBag's guess is that there was a whole lot of short covering today and in the next couple of weeks WFMI will come down a bit, but it is still trendier than Jessica Biel giving free blow jobs to bloggers (and trust me, that is going to be a huge trend).
In small cap news, RICK reported yesterday and they managed to not only shit the bed, but then they announced they were going to buy VCGH and shit all over their bed too (though to be fair, VCGH's bed was plenty shitty to begin with). Money McBags never thought he would be unhappy getting fucked by someone at RICK, and RICK not only fucked him, but they sent the 40 year old C-section showing, needle marks in the arm having, 2pm shift D-team dancer to do the job. Jeesh. Could they at least kiss me next time before they fuck me? Actually, scratch that. I mean I love the lovely ladies at Rick's who express themselves through dance to pay their college tuition, but they probably have more lip herpes than Richard Simmons has anal warts, so they can hold off on the kissing. Anyway, RICK reported the quarter that Money McBags had feared since they bought their Las Vegas club. You see, in order to win business in Vegas, Rick's pays the fuck out of cab drivers to bring patrons to their club. It is labeled as marketing costs, but it is payment of cash to cab drivers as clubs compete for traffic. All of the clubs kind of collude to keep that price to around $20, but to gain business and to slap their cocks on the table and let other club owners know they are serious, RICK had been occasionally upping the ante to as much as $100. Well it looks like in this quarter that occasional upped ante was both not occasional and was so far up that it gave itself a cerebral edema from hypobaropathy. Rick's marketing costs soared by $1.7MM to $2.9MM and treated their earnings like an Alabama professor after learning she wouldn't be tenured. Now on the call they said the marketing increase was related to more than just the Vegas club and that the Vegas club turned a profit in January and should be profitable for this Q, so that makes Money McBags feel a bit better, like how Jessica Simpson felt when she learned stupidity wasn't contagious, but it is a huge red flag. Their earnings missed the high end by $.08 which is actually slightly less than the uptick in marketing costs. Revenue was up a healthy 16.5% but it was achieved in the most unhealthy way, by paying people/cab drivers to show up. To Money McBags it is a huge concern and kept him out of the stock until a few months ago. Now on top of their shittastic performance, they announced a $45MM cash and stock acquisition of VCGH which will make them the largest strip club operator in the world. While Money McBags is a firm believer in bigger is better (such as the fine backsides of Carmen Kinsley and Alexis Texas), this deal has a ton of dilution as Rick is going to have to issue somwhere around 2.5MM shares and thus increase their share count by 25%. Rick's maintins that they will benefit from synergies such as corporate overhead, regional management, and shared thongs, and thinks EBITDA will be $25MM for the combined company. They also reaffirmed guidance for 2010 without VCGH of $.90 to $1.05 per share, so they are still fairly cheap on a p/e basis. The biggest problem is that Money McBags can't really analyze this deal because VCGH stopped filing financials months ago so there is no way to understand if their clubs are even remotely profitable. So you have a shitty quarter, a questionable deal, and a stock that has been on the move but is still cheap if you believe the marketing uptick was a one-time offense (and Money McBags has no idea about that). If you own RICK, it might not be a bad idea to trim a bit here, and if you're at Rick's, it might not be a bad idea to see some trim there. Alot of questions remain after this call such as will decreasing marketing costs hurt top line, what does Rick's new cap structure look like, and can a brother get a table dance? Unfortunately, after this quarter there will be no sex in Money McBags' champagne room and for those RICK's owners, you should really due some more work. Money McBags is holding for now, but leaning towards selling some as it's unclear how RICK will still hit their guidance for the year after missing this Q and how they will grow if they lower marketing costs, since if lower marketing costs were to allow them to grow, why wouldn't they have been lower this Q? Damn you logic.
There was one piece of macro news which caused a brief sell-off before the market put back on its pearl necklace and returned to the ball (and yes, all of those were very bad puns). The minutes came out today from the last FOMC meeting and the head of the Kansas City branch of the Fed, Thomas Hoenig (known at the Fed as T-Ho), was the one dissenting vote on interest rates. T-Ho got all up in Benny B's grill and axed him why they needed to say the fed funds rate would remain low for an "extended period," preferring to change the language to say the fed funds rate would remain low for "some time, and shit." The minutes also revealed that the Fed is starting to look at downsizing their balance sheet and selling into the market the toxic assets, I mean mortgages, they previously bought. The key message here being that further stimulus to help the economy may be less likely than Brooklyn Decker dumping Andy Roddick for the first guy eliminated from next season's The Biggest Loser. The Fed might actually be doing something smart here by looking to get in front of a bubble and stopping it before it happens rather than pulling an Alan Greenspan and blowing hot air into it like it was Andrea Mitchell's rectum.
In earnings news, Deere's profit climbed 19% and they raised forecasts thanks to strength in "large ag equipment", or what's more commonly known as: "Rosie O'Donnell's dildos." Also, WFMI not only had a kashi-tastic quarter as Money McBags predicted yesterday, but is was double fiber kashi-tastic. WFMI same store sales were up 3.5% and they gave total revenue guidance for 10.5% growth in 2010 while raising full year earnings guidance to $1.20 to $1.25 per share, about 10% above current estimates. Yeah, it was a good Q but they are now trading at around 25x 2011 earnings which wouldn't be so bad if they were growing by more than 10%. Of course, EBITDA was up 25% and they raised EBITDA guidance by about 5% to $635MM-$685MM for 2010 which means they're trading at around 7x to 7.5x 2010 EV/EBITDA which actually isn't all that unreasonable. Money McBag's guess is that there was a whole lot of short covering today and in the next couple of weeks WFMI will come down a bit, but it is still trendier than Jessica Biel giving free blow jobs to bloggers (and trust me, that is going to be a huge trend).

In small cap news, RICK reported yesterday and they managed to not only shit the bed, but then they announced they were going to buy VCGH and shit all over their bed too (though to be fair, VCGH's bed was plenty shitty to begin with). Money McBags never thought he would be unhappy getting fucked by someone at RICK, and RICK not only fucked him, but they sent the 40 year old C-section showing, needle marks in the arm having, 2pm shift D-team dancer to do the job. Jeesh. Could they at least kiss me next time before they fuck me? Actually, scratch that. I mean I love the lovely ladies at Rick's who express themselves through dance to pay their college tuition, but they probably have more lip herpes than Richard Simmons has anal warts, so they can hold off on the kissing. Anyway, RICK reported the quarter that Money McBags had feared since they bought their Las Vegas club. You see, in order to win business in Vegas, Rick's pays the fuck out of cab drivers to bring patrons to their club. It is labeled as marketing costs, but it is payment of cash to cab drivers as clubs compete for traffic. All of the clubs kind of collude to keep that price to around $20, but to gain business and to slap their cocks on the table and let other club owners know they are serious, RICK had been occasionally upping the ante to as much as $100. Well it looks like in this quarter that occasional upped ante was both not occasional and was so far up that it gave itself a cerebral edema from hypobaropathy. Rick's marketing costs soared by $1.7MM to $2.9MM and treated their earnings like an Alabama professor after learning she wouldn't be tenured. Now on the call they said the marketing increase was related to more than just the Vegas club and that the Vegas club turned a profit in January and should be profitable for this Q, so that makes Money McBags feel a bit better, like how Jessica Simpson felt when she learned stupidity wasn't contagious, but it is a huge red flag. Their earnings missed the high end by $.08 which is actually slightly less than the uptick in marketing costs. Revenue was up a healthy 16.5% but it was achieved in the most unhealthy way, by paying people/cab drivers to show up. To Money McBags it is a huge concern and kept him out of the stock until a few months ago. Now on top of their shittastic performance, they announced a $45MM cash and stock acquisition of VCGH which will make them the largest strip club operator in the world. While Money McBags is a firm believer in bigger is better (such as the fine backsides of Carmen Kinsley and Alexis Texas), this deal has a ton of dilution as Rick is going to have to issue somwhere around 2.5MM shares and thus increase their share count by 25%. Rick's maintins that they will benefit from synergies such as corporate overhead, regional management, and shared thongs, and thinks EBITDA will be $25MM for the combined company. They also reaffirmed guidance for 2010 without VCGH of $.90 to $1.05 per share, so they are still fairly cheap on a p/e basis. The biggest problem is that Money McBags can't really analyze this deal because VCGH stopped filing financials months ago so there is no way to understand if their clubs are even remotely profitable. So you have a shitty quarter, a questionable deal, and a stock that has been on the move but is still cheap if you believe the marketing uptick was a one-time offense (and Money McBags has no idea about that). If you own RICK, it might not be a bad idea to trim a bit here, and if you're at Rick's, it might not be a bad idea to see some trim there. Alot of questions remain after this call such as will decreasing marketing costs hurt top line, what does Rick's new cap structure look like, and can a brother get a table dance? Unfortunately, after this quarter there will be no sex in Money McBags' champagne room and for those RICK's owners, you should really due some more work. Money McBags is holding for now, but leaning towards selling some as it's unclear how RICK will still hit their guidance for the year after missing this Q and how they will grow if they lower marketing costs, since if lower marketing costs were to allow them to grow, why wouldn't they have been lower this Q? Damn you logic.

Wednesday, February 10, 2010
2/10/10 Midday Report: Bernanke's statement stuns meteorologists, causes it to rain on market's parade in the middle of a snowstorm
The big news moving the market down today was the statement from Ben Bernanke about the FED's future policy plans. Bernanke was supposed to testify in front of the House Financial Services Committee but the snow storm in Washington caused the hearing to be postponed giving Barney Frank more time to make snow angels and less time to suck at his job. Bernanke did release his full statement which serves to make Crime and Punishment read like a fucking Dr. Seuss book (I will kill her with an axe, I will kill her with hot wax. It will be an act of enormous enormance! No rational performer's performed this performance!). I'm not saying it was boring to read, but Ambien is said to be suing Bernanke's statement for patent infringement. However, since Money McBags is here to serve the people, he made it through the whole statement and can sum it up in fourteen words: "We did a bunch of shit, now we are going to try other shit." The important parts are that eventually rates will rise (duh), though not in the immediate future, and in the meantime, the FED will investigate other ways to control interest rates and bank lending, such as paying banks interest on reserve balances held at the FED. Below are Bernanke's actual words on this (no jokes, real information):
"By increasing the interest rate on reserves, the Federal Reserve will be able to put significant upward pressure on all short-term interest rates, as banks will not supply short-term funds to the money markets at rates significantly below what they can earn by holding reserves at the Federal Reserve Banks. Actual and prospective increases in short-term interest rates will be reflected in turn in longer- term interest rates and in financial conditions more generally"
The FED has also been developing a number of additional tools to use to reduce the large quantity of reserves held by the banking system. Those tools include offering term deposits, selling securities, and using reverse repos and their more deliciously effective cousin, the reverse cowboy.
In macro news, the US trade deficit increased, widening to $40B as both exports and imports increased. However, the rise in the dollar over the last couple of months may be hurting export growth in a classic Catch-22 situation, like mark to market accounting for bank balance sheets in a declining asset economy or finding Gia Carangi in your bed in 1985 and not having any condoms. While the trade gap was driven to some degree by a larger quantity of petroleum being imported, and while a 3% growth in exports is still growth, the US needs exports to take off like a young Milton Friedman in the mid 1940s in the University of Chicago Economics department where he proved the hypothesis that chicks dig rising permanent income (generally speaking).
Internationally, China's exports grew 21% while imports grew 85%. Container companies were said to have raised their shipping rates as export growth is causing steel containers to become more scarce in China than Andrew Johnson supporters in 1867 or female smurfs. The export growth in China has increased the calls to unpeg the renminbi and let it float to reflect its actual value, of course if it were up to Money McBags, he would just peg all currency to the the Vietnamese Dong (and yes, learning that Vietnam's currency is named the dong was pure comic gold for Money McBags, like whe he ran in to Tiger Wang on linkedin. Of course it does make Money McBags wonder if Lexington Steele would be the richest man in Vietnam due to the amount of dong he carries. Thanks, and don't forget to tip the waitress, though not too much because she has a bit of vertigo).
And we can't forget about Greece where civil servants went on strike and walked off the job for 24 hours thus shutting down airports, hospitals, and schools, in their attempt to become Camden, New Jersey. The EU's bailout will force the country to freeze salaries, raise the retirement age, and require citizens to purchase deodorant. But it's nice to see the workers protesting these cuts becuase I am sure they didn't receive any benefits from the enormous amount of debt taken on by the Greek government (and yes that was sarcasm).
In stock news, The New York Times had a quarter that beat expectations but the company continues to run a declining and outdated business. Their newspaper advertising revenue was down 17%, slightly better than the 30% decline from the first three quarters of the year, but still about as good as Emo Phillips hosting a Def Comedy Jam remake or Jennifer Love Hewitt's ass. New director of strategy, Phil Von Werescrewed, said "we expect the newspaper advertising revenue to level out any quarter now, unfortunately that level is going to be zero, so we're actively looking at new ways to be profitable, like shutting down, or restarting out dauggerotype business." In comparison to the Times' 1940's business, BIDU announced first quarter revenues to be above estimates as they gained advertising dollars from Google's potential pull out of China (which would make GOOG the most famous thing to pull out of Chyna since Triple H).
In small cap news, DFZ continues to rise after their huge Q which Money McBags broke down for you yesterday. Money McBags did have a chance to go through their call last night and it all sounded pretty good. They did say they expect to be unprofitable for the next six months which is consistent with previous years as the first six months of the calendar year is mostly replacement and replenishment business (hence their desire to make an acquisition to counter the seasonality of the slipper business). However, they did guide for slight revenue growth, though to be somewhat offset by an increase in marketing, but gross margins should be over 40% for the year, operating margins between 10% and 12%, and they are having no input pricing issues in China. The company has earned $.95 so far this year, so let's just call it $.90 in total for the fiscal year assuming a loss of $.05 in the next two quarters (though Money McBags thinks they might actually earn a profit with international sales increasing and the Dearfoam brand getting increased marketing, but whatever). They are now trading at 11x this number which is for the fiscal year ending in June (so not even really forward earnings). That is a ridiculously low multiple for a cheap growing company with a solid balance sheet. Money McBags thinks this is at a minimum at $12 stock but could easily see $15 if they continue to execute.
"By increasing the interest rate on reserves, the Federal Reserve will be able to put significant upward pressure on all short-term interest rates, as banks will not supply short-term funds to the money markets at rates significantly below what they can earn by holding reserves at the Federal Reserve Banks. Actual and prospective increases in short-term interest rates will be reflected in turn in longer- term interest rates and in financial conditions more generally"
The FED has also been developing a number of additional tools to use to reduce the large quantity of reserves held by the banking system. Those tools include offering term deposits, selling securities, and using reverse repos and their more deliciously effective cousin, the reverse cowboy.
In macro news, the US trade deficit increased, widening to $40B as both exports and imports increased. However, the rise in the dollar over the last couple of months may be hurting export growth in a classic Catch-22 situation, like mark to market accounting for bank balance sheets in a declining asset economy or finding Gia Carangi in your bed in 1985 and not having any condoms. While the trade gap was driven to some degree by a larger quantity of petroleum being imported, and while a 3% growth in exports is still growth, the US needs exports to take off like a young Milton Friedman in the mid 1940s in the University of Chicago Economics department where he proved the hypothesis that chicks dig rising permanent income (generally speaking).

Internationally, China's exports grew 21% while imports grew 85%. Container companies were said to have raised their shipping rates as export growth is causing steel containers to become more scarce in China than Andrew Johnson supporters in 1867 or female smurfs. The export growth in China has increased the calls to unpeg the renminbi and let it float to reflect its actual value, of course if it were up to Money McBags, he would just peg all currency to the the Vietnamese Dong (and yes, learning that Vietnam's currency is named the dong was pure comic gold for Money McBags, like whe he ran in to Tiger Wang on linkedin. Of course it does make Money McBags wonder if Lexington Steele would be the richest man in Vietnam due to the amount of dong he carries. Thanks, and don't forget to tip the waitress, though not too much because she has a bit of vertigo).
And we can't forget about Greece where civil servants went on strike and walked off the job for 24 hours thus shutting down airports, hospitals, and schools, in their attempt to become Camden, New Jersey. The EU's bailout will force the country to freeze salaries, raise the retirement age, and require citizens to purchase deodorant. But it's nice to see the workers protesting these cuts becuase I am sure they didn't receive any benefits from the enormous amount of debt taken on by the Greek government (and yes that was sarcasm).
In stock news, The New York Times had a quarter that beat expectations but the company continues to run a declining and outdated business. Their newspaper advertising revenue was down 17%, slightly better than the 30% decline from the first three quarters of the year, but still about as good as Emo Phillips hosting a Def Comedy Jam remake or Jennifer Love Hewitt's ass. New director of strategy, Phil Von Werescrewed, said "we expect the newspaper advertising revenue to level out any quarter now, unfortunately that level is going to be zero, so we're actively looking at new ways to be profitable, like shutting down, or restarting out dauggerotype business." In comparison to the Times' 1940's business, BIDU announced first quarter revenues to be above estimates as they gained advertising dollars from Google's potential pull out of China (which would make GOOG the most famous thing to pull out of Chyna since Triple H).


In small cap news, DFZ continues to rise after their huge Q which Money McBags broke down for you yesterday. Money McBags did have a chance to go through their call last night and it all sounded pretty good. They did say they expect to be unprofitable for the next six months which is consistent with previous years as the first six months of the calendar year is mostly replacement and replenishment business (hence their desire to make an acquisition to counter the seasonality of the slipper business). However, they did guide for slight revenue growth, though to be somewhat offset by an increase in marketing, but gross margins should be over 40% for the year, operating margins between 10% and 12%, and they are having no input pricing issues in China. The company has earned $.95 so far this year, so let's just call it $.90 in total for the fiscal year assuming a loss of $.05 in the next two quarters (though Money McBags thinks they might actually earn a profit with international sales increasing and the Dearfoam brand getting increased marketing, but whatever). They are now trading at 11x this number which is for the fiscal year ending in June (so not even really forward earnings). That is a ridiculously low multiple for a cheap growing company with a solid balance sheet. Money McBags thinks this is at a minimum at $12 stock but could easily see $15 if they continue to execute.
Friday, January 29, 2010
1/29/10 Midday Report: Size doesn't matter as 6% GDP expansion fails to stimulate the market
The market is bouncing around today even though GDP grew 5.7%, the fastest pace in 6 years and beat estimates of 4.7% growth. The upside was led by a restocking of inventories from their depressed levels (and inventories were more depressed than Kathy Griffin's bikini waxer the time she ran out of rubber gloves). The change in inventories accounted for 3.4% of the growth with purchases of equipment and software up 13%, negating the 15% drop in commercial construction because building cardboard boxes is so much cheaper than actual homes. So the question becomes is this a one quarter inventory rebuilding and stimulus induced anomaly or are we really on the way to a recovery? In the delightful Elisabeth Kubler-Ross's model on the stages of grief (and for those who missed Ms. Kubler-Ross's induction into the National Women's Hall of Fame in 2007, the finger sandwiches were to die for), the economy has passed steps one and two by moving past denial (we are definitely fucked) and anger (openly calling for Dick Fuld to have his dick folded) and is now in the bargaining stage (please hire me, please, please). Unfortunatley the next stage is depression, which hopefully isn't caused by another market crash when inventories fail to turn and/or by China's bubble bursting like Christina Hendricks' bustier. Of course the last stage is acceptance and with any luck we will be accepting growth and recovery and not the realization that we are Japan circa 1989 or Taylor Rain's lovely backside in her brilliant performance in 2004's much overlooked film, Apprentass.
What is most concerning to Money McBags is that the market has been selling good news and is trading down now that the expected results are coming in much better. Of the 195 companies in the S&P 500 that have reported earnings since Jan. 11, 154 have beaten analysts’ estimates, according to Bloomberg data. That is an amazing stat and yet the market rally seems to have fizzled out like Lindsay Lohan's singing career (and acting career, and pretty much anything other than her whoring career, which actually makes us all winners).
The other big news of the day is that Ben Bernanke was confirmed by the Senate for another 4 year term by a 70 to 30 vote. The thirty who voted against him also voted for Mountain Dew in the Pepsi challenge, Curly Joe as their favorite of the 3 Stooges, and Anna Karenina as their favorite Tolstoy novel. Money McBags is a Bernanke supporter and thinks he has done a perfectly reasonable job as Fed Chairman, so kudos and huzzah for the Senate who took a wide stance and voted bi-partisanly on this one.
In stock news, MSFT earnings were up 60% thanks to Windows 7 and a little something they refer to as a "monopoly." They beat estimates by $.15 by earning $.74 per share and promised that with earnings like this Bill Gates may finally be able to move out of his mother's basement. Amazon also put up a huge quarter with sales rising 43% and earnings coming in at a robust $.85 per share, well ahead of the $.72 estimates. They also announced a $2B share buyback which boggles the mind considering that they are trading at 50x next year's earnings and with the iPad coming in to the market and potentially taking share away from the Kindle. Why a commodity business with low barriers to entry should trade at 50x is beyond me, but then again, so is M-theory and all of it's absurdly thought out 11 dimensions.
In small cap news MED and ZAGG continue to trade down while EBIX gives back some of their gains from yesterday. CRUS is also down despite their better than street guidance yesterday and run of analyst upgrades today. Money McBags did dip his toe into the CRUS waters yesterday (and it was delightfully stripper piss warm) and buy a small position so go buy some iPhones. Next week promises to be a wild week in the small cap space with more earnings announcements than Jack Nicholson has chins, so enjoy your weekend and be prepared.


What is most concerning to Money McBags is that the market has been selling good news and is trading down now that the expected results are coming in much better. Of the 195 companies in the S&P 500 that have reported earnings since Jan. 11, 154 have beaten analysts’ estimates, according to Bloomberg data. That is an amazing stat and yet the market rally seems to have fizzled out like Lindsay Lohan's singing career (and acting career, and pretty much anything other than her whoring career, which actually makes us all winners).

The other big news of the day is that Ben Bernanke was confirmed by the Senate for another 4 year term by a 70 to 30 vote. The thirty who voted against him also voted for Mountain Dew in the Pepsi challenge, Curly Joe as their favorite of the 3 Stooges, and Anna Karenina as their favorite Tolstoy novel. Money McBags is a Bernanke supporter and thinks he has done a perfectly reasonable job as Fed Chairman, so kudos and huzzah for the Senate who took a wide stance and voted bi-partisanly on this one.
In stock news, MSFT earnings were up 60% thanks to Windows 7 and a little something they refer to as a "monopoly." They beat estimates by $.15 by earning $.74 per share and promised that with earnings like this Bill Gates may finally be able to move out of his mother's basement. Amazon also put up a huge quarter with sales rising 43% and earnings coming in at a robust $.85 per share, well ahead of the $.72 estimates. They also announced a $2B share buyback which boggles the mind considering that they are trading at 50x next year's earnings and with the iPad coming in to the market and potentially taking share away from the Kindle. Why a commodity business with low barriers to entry should trade at 50x is beyond me, but then again, so is M-theory and all of it's absurdly thought out 11 dimensions.
In small cap news MED and ZAGG continue to trade down while EBIX gives back some of their gains from yesterday. CRUS is also down despite their better than street guidance yesterday and run of analyst upgrades today. Money McBags did dip his toe into the CRUS waters yesterday (and it was delightfully stripper piss warm) and buy a small position so go buy some iPhones. Next week promises to be a wild week in the small cap space with more earnings announcements than Jack Nicholson has chins, so enjoy your weekend and be prepared.

Wednesday, January 27, 2010
1/27/10 Midday Report: In bid to increase approval ratings, Obama to unveil Apple Tablet at State of the Union address as a panacea for US budget problems
The market continues to limp it's way down as investors await tonight's State of the Union address where President Obama is likely to whip out his small business tax breaks and smack them against a non-defense discretionary spending budget freeze. This budget freeze supposedly applies to 17% of the Federal budget and will have enough loopholes in it to make it less well-followed than the failed reality TV series: Federal Reserve Bank Governor Idol (though Sandra Pianalto yelling at Chuck Evans for leaving the toilet seat up in the house was must see TV). It does likely mean that the president won't be getting the X-Box he asked for for his birthday as times are tough. In addition to Obama going after the budget tonight, Apple is set to finally release their new tablet which has techies more excited than they were for the release of Avatar, extra-strength Accutane, or Olivia Munn's Princess Leia photos. Honestly, Money McBags has not seen anything this eagerly anticipated since the release of those vapidly redundant Harry Potter books or Hanna Hilton's first girl on girl scene (and Money McBags gave that two bums up). The tablet is supposed to be so awesome that it is said to have cured Steve Jobs' cancer and to run on the tears of baby unicorns. And finally, the FOMC is meeting today with Bernanke expected to keep rates at their current 0 to 25bps or what we in the business call "free."
While the market awaits that news, there were some macro-reports that came out which highlight the worries people are starting to get about the economy. New home sales fell in December by 7.6% and were short of expectations as analysts expected sales to rise (and I believe this now makes analysts' incorrect prediction of the simple 50-50 guess at the direction of home sales statistically significant at the 95% level, so they've got that going for them). Home sales were down as a result of the government tax breaks drying up and the forgotten fact that no one has any money. Plus as the job market is more frozen than an Alaskan's nuts after a midnight skinny dip in Lake Chilkoot (and yes that is really the name of Lake in Alaska), people simply aren't moving.
In world news, Greece teeters on bankruptcy causing investors to stock up on credit default swaps of sovereign debt and all the tzatziki sauce on which they can get their hands. Greece is trying to remedy the situation by pawning off 25B of Euro bonds to China as well as stadium naming rights to the Parthenon, and the Golden Fleece. The flight to quality and away from sovereign debt like Greece has caused one month treasuries to have a negative yield for the first time since March of last year which is about as good of an omen for the stock market as stairs are for Stephen Hawking.
Berkshire Hathaway's B shares are shooting up today like a young Drew Barrymore as word is they will be added to the S&P 500 index after their acquisition of BNI. Also, Toyota announced they will be shutting down production on eight lines of cars which make up 57% of their 2009 sales due to problems with the accelerator pedals seemingly caused by something called a friction lever. A friction lever joke is way too easy for Money McBags but this bears watching as the street wonders if Toyota has started to slack on their quality which has been their competitive advantage. In other stock news, YHOO turned a profit despite a 4% drop in year over year revenue. Revenue was up 10% sequentially and management said they see search revenue stabilizing so any investor who wants to own a portfolio of market laggards, now is your time to buy.
As for small cap stocks, ZAGG once again continues to trade down making Money McBags' bet on 12/31/09 seem even better as it was likely risk free. So just remember, betting against Money McBags is like challenging Greg Oden to a cock off (very NSFW or actually anyone, but the news needs reporting), you can't possibly win. And SMCI put up a huge quarter. Now SMCI basically makes custom servers and server solutions for businesses, usually being the first to market with new INTC chips, hence the Nehalem release has been driving new business for them. They just put up $.22 of earning per share on $182MM of revenue (up 42% y/y), easily beating analyst estimates of $.17 and $160MM. The company also gave above street guidance of $.18 to $.21 eps for next Q and $180MM of revenue in what is typically a down quarter for the industry. SMCI is an extremely well run little niche company with $82MM of cash on their balance sheet and no debt. They have a competitive advantage in that they are small and nimble (like Speedy Gonzales or the slightly smaller and more nimble, Shawn Johnson) and therefore can be first to market and customize at the same time. The company may be peaking but on the call management said they could get back to 30% growth rates as the end of the year should be good for them with AMD and INTC introducing new products. Estimates for fiscal 2011 are for around $1.10 and they are currently trading at 13 or so times that not including their cash after today's run up. This should be a cyclical company and this may be the top of the cycle as they have just strung together some very good quarters so Money McBags would not be buying today as the easy money has likely been made. That said, this really is a quality company and has proven over time that they are good at what they do and well managed. Should there be a dip, this is definitely a company to accumulate but either way it is worth doing your own research here as they could continue to outperform.

Subscribe to:
Posts (Atom)